Unverified Insight Portal Information Cannot Justify Reassessment Without a Verified Taxpayer-Specific Income-Escape Nexus or Demonstrated Application...
Assessing Officer jurisdiction after statutory transfer invalidates reassessment notices issued by transferor officers and nullifies resulting proceed...
Consequential appeal-effect orders must implement rectification deleting working-capital adjustments and reconsider the resulting arm's-length range c...
Discounted cash flow valuation protects share premium where projections are reasonable, while audited book expenses defeat unexplained-expenditure add...
Section 54 construction relief survives pre-transfer commencement when completion occurs within the statutory period, excluding ineligible spouse-owne...
Judicial review of Settlement Commission orders is limited to...
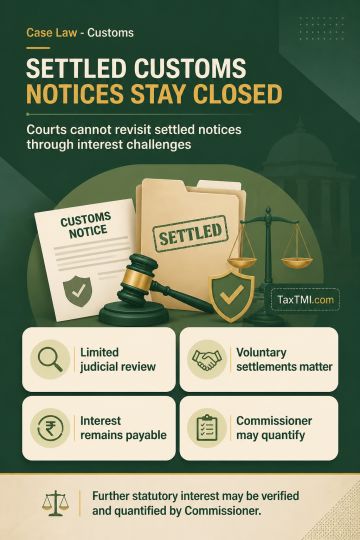
Judicial review of settlement orders cannot reopen settled customs notices, while statutory interest remains subject to verification and quantification.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Judicial review of Settlement Commission orders is limited to jurisdictional or statutory infirmity, prejudice, fraud, bias or malice and cannot operate as an appellate reassessment of the underlying adjudication. Where parties voluntarily settle proceedings arising from a show cause notice without pursuing the statutory appeal, they cannot reopen the notice's validity on limitation or reasonable-period grounds by challenging a consequential interest direction. Statutory interest remains a consequence of customs duty liability despite settlement of the duty quantum. Verification and quantification of further interest by the jurisdictional Commissioner may therefore be directed, subject to any independently maintainable challenge to the statutory computation.
Judicial review of Settlement Commission orders is limited to jurisdictional or statutory infirmity, prejudice, fraud, bias or malice and cannot operate as an appellate reassessment of the underlying adjudication. Where parties voluntarily settle proceedings arising from a show cause notice without pursuing the statutory appeal, they cannot reopen the notice's validity on limitation or reasonable-period grounds by challenging a consequential interest direction. Statutory interest remains a consequence of customs duty liability despite settlement of the duty quantum. Verification and quantification of further interest by the jurisdictional Commissioner may therefore be directed, subject to any independently maintainable challenge to the statutory computation.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4912