Alternative statutory remedy under GST bars writ challenge where classification, notice variance, and hearing disputes require factual appellate revie...
Duplicate PAN cancellation timeframe requires prior administrative representation before judicial intervention, ensuring a time-bound decision on the ...
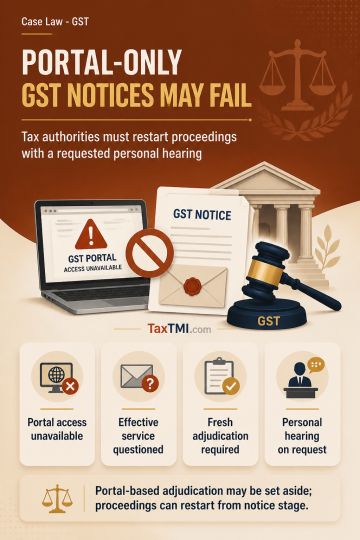
GST show cause notices served only through the portal after cancellation of registration do not constitute effective service where the taxpayer cannot access the portal. Adjudication based on such service is liable to be set aside, with the tax authorities permitted to restart proceedings from the show cause notice stage in accordance with law. In fresh proceedings, a personal hearing must be provided where the taxpayer requests it under the statutory requirement. The discussion relies on decisions treating portal-only communication after cancellation as inconsistent with effective notice and procedural fairness.
GST show cause notices served only through the portal after cancellation of registration do not constitute effective service where the taxpayer cannot access the portal. Adjudication based on such service is liable to be set aside, with the tax authorities permitted to restart proceedings from the show cause notice stage in accordance with law. In fresh proceedings, a personal hearing must be provided where the taxpayer requests it under the statutory requirement. The discussion relies on decisions treating portal-only communication after cancellation as inconsistent with effective notice and procedural fairness.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4894