Duplicate PAN allocation requires record verification and deactivation reasons before assessment-related transactions can be attributed to an assessee...
Faceless assessment safeguards require requested personal hearings and adequate final show-cause response time, failing which reassessment is required...
Embezzlement losses in charitable institutions remain allowable when misappropriation is established, irrecoverable, and not a specified-person benefi...
National long-distance undertaking status supports deduction where separately licensed infrastructure, resources, revenue, and expenditure establish c...
Agency reimbursement income follows contractual deposit-liability computation, while pending deposit collections do not constitute deemed-dividend loa...
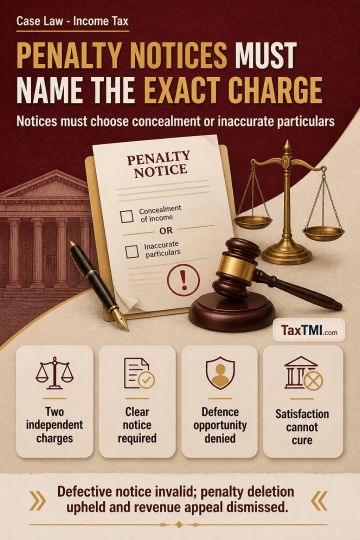
Penalty notices under section 271(1)(c) must clearly identify whether the charge concerns concealment of income or furnishing inaccurate particulars. The two limbs are independent and may require different explanations and treatment; therefore, a notice retaining both alternatives without specifying the applicable limb denies the assessee a proper opportunity to defend. Recording satisfaction to initiate penalty proceedings does not cure this defect. Applying this principle, the High Court treated the defective notice as invalid, upheld deletion of the penalty, and dismissed the revenue's appeal.
Penalty notices under section 271(1)(c) must clearly identify whether the charge concerns concealment of income or furnishing inaccurate particulars. The two limbs are independent and may require different explanations and treatment; therefore, a notice retaining both alternatives without specifying the applicable limb denies the assessee a proper opportunity to defend. Recording satisfaction to initiate penalty proceedings does not cure this defect. Applying this principle, the High Court treated the defective notice as invalid, upheld deletion of the penalty, and dismissed the revenue's appeal.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4897