Educational approval requires mandatory State registration, but incidental surplus and trustee-owned land do not prove private benefit or profit motiv...
Judicial review of settlement orders cannot reopen settled customs notices, while statutory interest remains subject to verification and quantificatio...
Customs Broker licence lending for consideration justified revocation where exporter authorisation and client verification obligations were also breac...
Fraudulent import documents suspend limitation protection, while redemption of confiscated goods requires duty and interest despite bona fide purchase...
Page of 4932
Press 'Enter' after typing page number.
2501 to 2520 of 98625 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
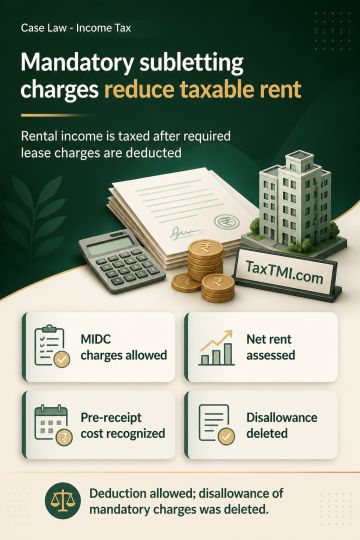
Subletting charges paid to MIDC as a mandatory condition for subletting leasehold property are treated as an integral cost of earning rental income. Taxable income from house property is therefore computed on net rental income after reducing those charges. The standard deduction available for house property income under section 24(a) does not prevent deduction of such pre-receipt expenditure, because the charges are necessary to commercially exploit the leasehold property through subletting. The disallowance of the charges was deleted and the deduction was allowed.
Subletting charges paid to MIDC as a mandatory condition for subletting leasehold property are treated as an integral cost of earning rental income. Taxable income from house property is therefore computed on net rental income after reducing those charges. The standard deduction available for house property income under section 24(a) does not prevent deduction of such pre-receipt expenditure, because the charges are necessary to commercially exploit the leasehold property through subletting. The disallowance of the charges was deleted and the deduction was allowed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4932