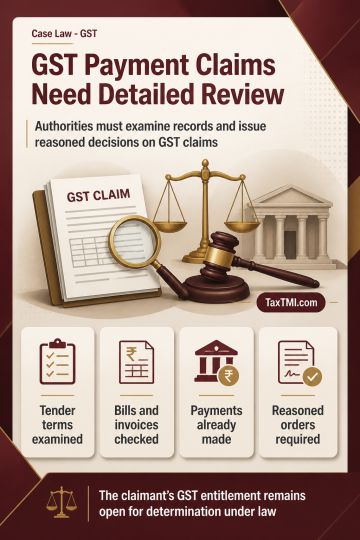
GST payment representations require record-based, reasoned decisions while substantive entitlement remains open for determination by competent authori...
Reassessment sanction under extended limitation required approval from the competent specified authority, invalidating proceedings approved by an inco...
Internal CUP benchmarking for fixed-rate Masala Bonds prevails over floating external comparables, eliminating the related transfer-pricing adjustment...
Jurisdictional validity of revision notices: incorrect official capacity and mere change of opinion invalidate revision of property income assessments...
Rectification under section 154 cannot withdraw a deduction...
Rectification of debatable deduction claims cannot reverse scrutiny-approved co-operative society interest income deductions as apparent record errors.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Rectification under section 154 cannot withdraw a deduction under section 80P(2)(a)(i) that was expressly claimed and accepted after scrutiny where its eligibility involves a debatable statutory question. Interest income was claimed as business income attributable to a co-operative society's activities and allowed after verification under section 143(3). The subsequent view that the claim was inconsistent with decisions concerning section 80P(2)(d) required reconsideration of an already examined claim, rather than correction of a mistake apparent from the record. The rectification and appellate orders reversing the deduction were therefore set aside.
Rectification under section 154 cannot withdraw a deduction under section 80P(2)(a)(i) that was expressly claimed and accepted after scrutiny where its eligibility involves a debatable statutory question. Interest income was claimed as business income attributable to a co-operative society's activities and allowed after verification under section 143(3). The subsequent view that the claim was inconsistent with decisions concerning section 80P(2)(d) required reconsideration of an already examined claim, rather than correction of a mistake apparent from the record. The rectification and appellate orders reversing the deduction were therefore set aside.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4935