Limitation after transfer-pricing remand: fresh TPO reference did not extend the assessment deadline, rendering the consequential assessment time-barr...
Interim judicial restraint on tax deduction prevents default, while supporting reasonable cause and penalty deletion for foreign-leg LFC reimbursement...
Palmolein classification defeated the crude-oil concession; material misdeclaration sustained recovery and confiscation, while separate false-document...
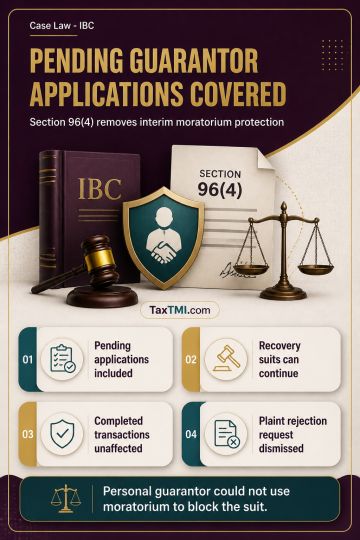
Section 96(4) of the Insolvency and Bankruptcy Code applies retroactively to pending insolvency applications involving personal guarantors to corporate debtors. The exclusion removes the pre-admission interim moratorium that could otherwise delay recovery proceedings; it affects pending transactions rather than completed transactions. The phrase "is filed" includes applications filed before the amendment's commencement but still pending thereafter. Consequently, the personal guarantor could not rely on an interim moratorium to bar the suit, and the request to reject the plaint on that basis was dismissed.
Section 96(4) of the Insolvency and Bankruptcy Code applies retroactively to pending insolvency applications involving personal guarantors to corporate debtors. The exclusion removes the pre-admission interim moratorium that could otherwise delay recovery proceedings; it affects pending transactions rather than completed transactions. The phrase "is filed" includes applications filed before the amendment's commencement but still pending thereafter. Consequently, the personal guarantor could not rely on an interim moratorium to bar the suit, and the request to reject the plaint on that basis was dismissed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4891