Judicial discipline requires consistent reassessment treatment where identical facts were decided for the same taxpayer in the preceding assessment ye...
Agreement-date stamp valuation requires the same registered property, fixed consideration, and qualifying payment; an unrelated prior booking cannot a...
Page of 4894
Press 'Enter' after typing page number.
221 to 240 of 97867 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
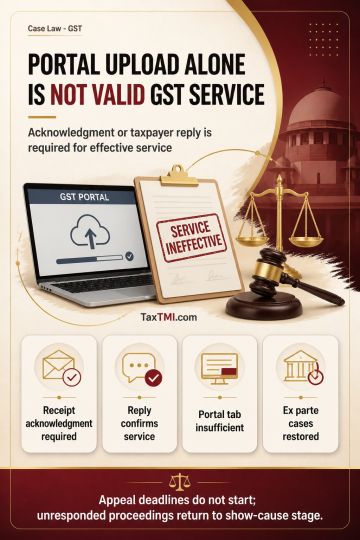
Portal-only uploading of a show-cause notice or order-in-original in the GST Common Portal's "View Additional Notices and Orders" tab does not by itself constitute valid service. Service is sufficient only where receipt is acknowledged or the taxpayer files a reply. The retrospective amendment permitting GST Rules functions through the Common Portal does not designate it as a formal mode of service for notices or adjudication orders. Consequently, portal-only upload does not commence the appeal limitation period for contested adjudication orders; where ex parte adjudication followed without a reply, proceedings are restored to the show-cause notice stage.
Portal-only uploading of a show-cause notice or order-in-original in the GST Common Portal's "View Additional Notices and Orders" tab does not by itself constitute valid service. Service is sufficient only where receipt is acknowledged or the taxpayer files a reply. The retrospective amendment permitting GST Rules functions through the Common Portal does not designate it as a formal mode of service for notices or adjudication orders. Consequently, portal-only upload does not commence the appeal limitation period for contested adjudication orders; where ex parte adjudication followed without a reply, proceedings are restored to the show-cause notice stage.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4894