Compulsorily convertible debentures remain debt before conversion, preventing transfer-pricing and interest-deduction disallowances on the stated fact...
Stock-in-trade transfer taxability follows possession and consideration, not later conveyance registration, limiting deemed-value provisions to the ac...
Alternative statutory remedy under GST bars writ challenge where classification, notice variance, and hearing disputes require factual appellate revie...
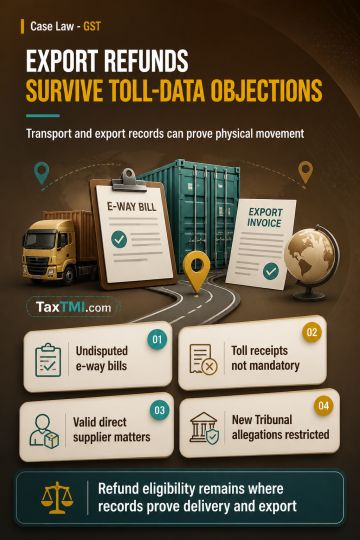
Refund of accumulated input tax credit on exported goods remains available where bill-to ship-to supplies are supported by undisputed e-way bills, transportation, export and banking records establishing delivery and export. GST law does not require movement to commence from the supplier's registered premises, and toll plaza receipts are not a mandatory condition for credit; toll data cannot override documentary proof of physical movement. Cancellation of upstream suppliers' registrations does not by itself invalidate credit where the direct supplier is validly registered and the claimant lacks involvement in upstream irregularities. Fresh allegations and unsupported evidence beyond the show cause notice cannot be raised at the Tribunal stage, absent exceptional circumstances under the applicable evidence rules.
Refund of accumulated input tax credit on exported goods remains available where bill-to ship-to supplies are supported by undisputed e-way bills, transportation, export and banking records establishing delivery and export. GST law does not require movement to commence from the supplier's registered premises, and toll plaza receipts are not a mandatory condition for credit; toll data cannot override documentary proof of physical movement. Cancellation of upstream suppliers' registrations does not by itself invalidate credit where the direct supplier is validly registered and the claimant lacks involvement in upstream irregularities. Fresh allegations and unsupported evidence beyond the show cause notice cannot be raised at the Tribunal stage, absent exceptional circumstances under the applicable evidence rules.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4886