Charitable character assessment preserves Section 80G approval despite inclusive spiritual teachings and incidental religious expenditure within the s...
Penalty proceedings for cash-loan acceptance require assessment proceedings and recorded Assessing Officer satisfaction; absent these, the proceedings...
Functional comparability governs software-service benchmarking: dissimilar companies are excluded, while related-party filters, margins and working-ca...
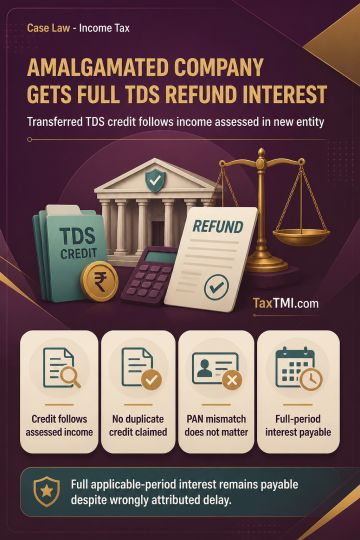
TDS credit transferred following amalgamation must be granted to the amalgamated entity where the related income is substantively assessed in its hands and the amalgamating entity has not claimed that credit. Section 199 read with Rule 37BA applies despite the TDS appearing under the amalgamating entity's PAN. Where the credit was claimed in the original and revised returns and subsequently allowed, refund interest under section 244A(1) is payable for the full applicable period. Delay cannot be excluded under section 244A(2) merely because the Assessing Officer wrongly attributes default to the taxpayer.
TDS credit transferred following amalgamation must be granted to the amalgamated entity where the related income is substantively assessed in its hands and the amalgamating entity has not claimed that credit. Section 199 read with Rule 37BA applies despite the TDS appearing under the amalgamating entity's PAN. Where the credit was claimed in the original and revised returns and subsequently allowed, refund interest under section 244A(1) is payable for the full applicable period. Delay cannot be excluded under section 244A(2) merely because the Assessing Officer wrongly attributes default to the taxpayer.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4937