Duplicate PAN allocation requires record verification and deactivation reasons before assessment-related transactions can be attributed to an assessee...
Faceless assessment safeguards require requested personal hearings and adequate final show-cause response time, failing which reassessment is required...
Embezzlement losses in charitable institutions remain allowable when misappropriation is established, irrecoverable, and not a specified-person benefi...
National long-distance undertaking status supports deduction where separately licensed infrastructure, resources, revenue, and expenditure establish c...
Agency reimbursement income follows contractual deposit-liability computation, while pending deposit collections do not constitute deemed-dividend loa...
Limitation for an assessment giving effect to appellate...
Limitation for consequential assessments runs from prescribed authority receipt, while verified purchases cannot be disallowed merely for unanswered summons.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
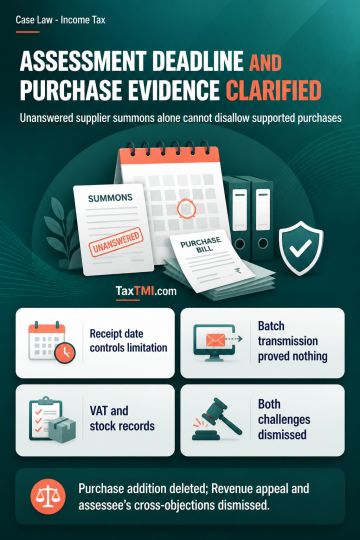
Limitation for an assessment giving effect to appellate directions runs from receipt or passing of the appellate order by the specified senior income-tax authorities, not from delivery to the Departmental Representative. Where no receipt date is recorded, internal transmission of a batch of orders does not establish earlier receipt, and the assessment may be treated as timely. Unexplained purchase expenditure cannot be added solely because suppliers did not answer summons when supplier existence, VAT verification, stock records, and corresponding sales support the transactions. The deletion of the purchase addition was sustained, while the Revenue's appeal and the assessee's cross-objections were dismissed.
Limitation for an assessment giving effect to appellate directions runs from receipt or passing of the appellate order by the specified senior income-tax authorities, not from delivery to the Departmental Representative. Where no receipt date is recorded, internal transmission of a batch of orders does not establish earlier receipt, and the assessment may be treated as timely. Unexplained purchase expenditure cannot be added solely because suppliers did not answer summons when supplier existence, VAT verification, stock records, and corresponding sales support the transactions. The deletion of the purchase addition was sustained, while the Revenue's appeal and the assessee's cross-objections were dismissed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4894