Alternative statutory remedy under GST bars writ challenge where classification, notice variance, and hearing disputes require factual appellate revie...
Duplicate PAN cancellation timeframe requires prior administrative representation before judicial intervention, ensuring a time-bound decision on the ...
Natural justice and pre-CIRP labour awards protect termination compensation, permitting withdrawal of court deposits despite later insolvency resoluti...
Page of 4886
Press 'Enter' after typing page number.
21 to 40 of 97705 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Commercial vehicles purchased during the stipulated period were...
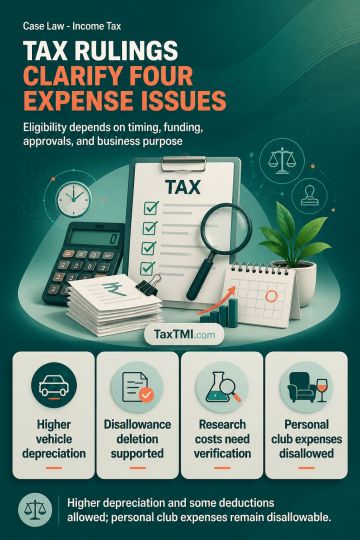
Higher depreciation for qualifying commercial vehicles, exempt-income disallowance, research deduction verification, and club-expense treatment clarified
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Commercial vehicles purchased during the stipulated period were treated as eligible for higher depreciation. For in-house research and development, deduction beyond expenditure approved by the prescribed authority requires verification of the difference between approved and actual expenditure before consequential allowance. Where interest-free funds exceed investments yielding exempt income, investments may be presumed to have been made from those funds, supporting deletion of the related disallowance under rule 8D(2)(iii). Club-facility expenses incurred in individuals' names or of a personal nature do not satisfy the requirement of being wholly and exclusively for business purposes and remain disallowable.
Commercial vehicles purchased during the stipulated period were treated as eligible for higher depreciation. For in-house research and development, deduction beyond expenditure approved by the prescribed authority requires verification of the difference between approved and actual expenditure before consequential allowance. Where interest-free funds exceed investments yielding exempt income, investments may be presumed to have been made from those funds, supporting deletion of the related disallowance under rule 8D(2)(iii). Club-facility expenses incurred in individuals' names or of a personal nature do not satisfy the requirement of being wholly and exclusively for business purposes and remain disallowable.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4886