Alternative statutory remedy under GST bars writ challenge where classification, notice variance, and hearing disputes require factual appellate revie...
Duplicate PAN cancellation timeframe requires prior administrative representation before judicial intervention, ensuring a time-bound decision on the ...
Natural justice and pre-CIRP labour awards protect termination compensation, permitting withdrawal of court deposits despite later insolvency resoluti...
Page of 4886
Press 'Enter' after typing page number.
21 to 40 of 97705 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
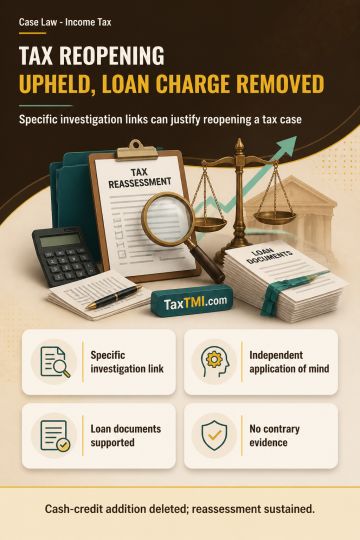
Reassessment based on Investigation Wing information may rest on tangible material where it specifically links alleged accommodation entries to the taxpayer's loan transaction, creating a live nexus and demonstrating independent application of mind rather than borrowed satisfaction. For an unsecured-loan credit, confirmation, PAN, tax return, audited financial statements, bank records, interest payments with tax deduction, and repayment can discharge the taxpayer's burden. Third-party investigation material alone does not displace this evidence without proof that the taxpayer paid cash for the loan or that the lender's funds belonged to the taxpayer. The reassessment was sustained, while the cash-credit addition was deleted.
Reassessment based on Investigation Wing information may rest on tangible material where it specifically links alleged accommodation entries to the taxpayer's loan transaction, creating a live nexus and demonstrating independent application of mind rather than borrowed satisfaction. For an unsecured-loan credit, confirmation, PAN, tax return, audited financial statements, bank records, interest payments with tax deduction, and repayment can discharge the taxpayer's burden. Third-party investigation material alone does not displace this evidence without proof that the taxpayer paid cash for the loan or that the lender's funds belonged to the taxpayer. The reassessment was sustained, while the cash-credit addition was deleted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4886