Embezzlement losses in charitable institutions remain allowable when misappropriation is established, irrecoverable, and not a specified-person benefi...
National long-distance undertaking status supports deduction where separately licensed infrastructure, resources, revenue, and expenditure establish c...
Agency reimbursement income follows contractual deposit-liability computation, while pending deposit collections do not constitute deemed-dividend loa...
Membership-consent thresholds for oppression petitions are satisfied by unchallenged voter-list consents, while unsupported forgery claims require pro...
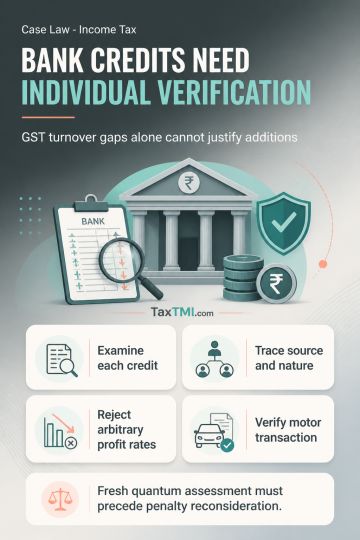
Unexplained bank credits require credit-wise verification; a difference between aggregate bank deposits and GST-reported turnover does not, by itself, establish unexplained money. The taxpayer must establish the nature and source of credits, while the assessment must examine sales receipts, inter-bank transfers, contra entries, redeposits, expenses and disclosed business results. Business-profit estimation must rely on the nature of trade, prior or later results, comparable cases or other relevant material rather than an arbitrary rate. Consequential penalty requires reconsideration after fresh quantum assessment. A Form 26AS entry showing tax collection on a motor vehicle transaction requires verification of whether the transaction was a purchase or sale before taxing any short-term capital gain.
Unexplained bank credits require credit-wise verification; a difference between aggregate bank deposits and GST-reported turnover does not, by itself, establish unexplained money. The taxpayer must establish the nature and source of credits, while the assessment must examine sales receipts, inter-bank transfers, contra entries, redeposits, expenses and disclosed business results. Business-profit estimation must rely on the nature of trade, prior or later results, comparable cases or other relevant material rather than an arbitrary rate. Consequential penalty requires reconsideration after fresh quantum assessment. A Form 26AS entry showing tax collection on a motor vehicle transaction requires verification of whether the transaction was a purchase or sale before taxing any short-term capital gain.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4888