Separate speaking orders on reopening objections are mandatory; deciding them within reassessment invalidates jurisdiction and precludes revival of st...
Compulsorily convertible debentures remain debt before conversion, preventing transfer-pricing and interest-deduction disallowances on the stated fact...
Stock-in-trade transfer taxability follows possession and consideration, not later conveyance registration, limiting deemed-value provisions to the ac...
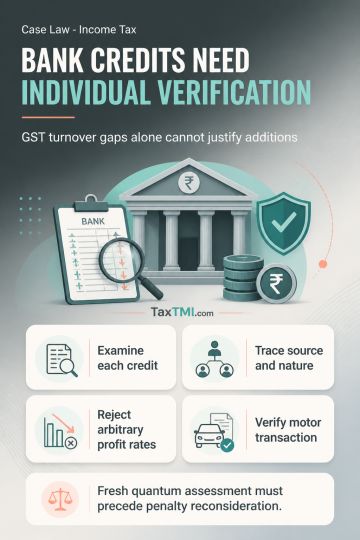
Unexplained bank credits require credit-wise verification; a difference between aggregate bank deposits and GST-reported turnover does not, by itself, establish unexplained money. The taxpayer must establish the nature and source of credits, while the assessment must examine sales receipts, inter-bank transfers, contra entries, redeposits, expenses and disclosed business results. Business-profit estimation must rely on the nature of trade, prior or later results, comparable cases or other relevant material rather than an arbitrary rate. Consequential penalty requires reconsideration after fresh quantum assessment. A Form 26AS entry showing tax collection on a motor vehicle transaction requires verification of whether the transaction was a purchase or sale before taxing any short-term capital gain.
Unexplained bank credits require credit-wise verification; a difference between aggregate bank deposits and GST-reported turnover does not, by itself, establish unexplained money. The taxpayer must establish the nature and source of credits, while the assessment must examine sales receipts, inter-bank transfers, contra entries, redeposits, expenses and disclosed business results. Business-profit estimation must rely on the nature of trade, prior or later results, comparable cases or other relevant material rather than an arbitrary rate. Consequential penalty requires reconsideration after fresh quantum assessment. A Form 26AS entry showing tax collection on a motor vehicle transaction requires verification of whether the transaction was a purchase or sale before taxing any short-term capital gain.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI