Embezzlement losses in charitable institutions remain allowable when misappropriation is established, irrecoverable, and not a specified-person benefi...
National long-distance undertaking status supports deduction where separately licensed infrastructure, resources, revenue, and expenditure establish c...
Agency reimbursement income follows contractual deposit-liability computation, while pending deposit collections do not constitute deemed-dividend loa...
Membership-consent thresholds for oppression petitions are satisfied by unchallenged voter-list consents, while unsupported forgery claims require pro...
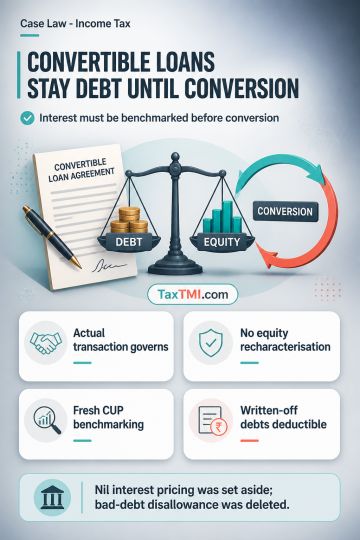
Transfer pricing rules require benchmarking the actual international transaction and generally prohibit re-characterising legally valid compulsorily convertible debentures as equity merely because another commercial structure appears preferable. Compulsory conversion, lack of repayment before conversion, and separate regulatory or accounting treatment do not alter their debt character until conversion. The nil arm's length price for interest was therefore set aside, with fresh benchmarking required using CUP or another permissible method. Bad debts written off are deductible where statutory conditions are met and debtor accounts are correspondingly extinguished; independent proof of irrecoverability is unnecessary. The bad-debt disallowance was deleted.
Transfer pricing rules require benchmarking the actual international transaction and generally prohibit re-characterising legally valid compulsorily convertible debentures as equity merely because another commercial structure appears preferable. Compulsory conversion, lack of repayment before conversion, and separate regulatory or accounting treatment do not alter their debt character until conversion. The nil arm's length price for interest was therefore set aside, with fresh benchmarking required using CUP or another permissible method. Bad debts written off are deductible where statutory conditions are met and debtor accounts are correspondingly extinguished; independent proof of irrecoverability is unnecessary. The bad-debt disallowance was deleted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4888