Duplicate PAN allocation requires record verification and deactivation reasons before assessment-related transactions can be attributed to an assessee...
Faceless assessment safeguards require requested personal hearings and adequate final show-cause response time, failing which reassessment is required...
Embezzlement losses in charitable institutions remain allowable when misappropriation is established, irrecoverable, and not a specified-person benefi...
National long-distance undertaking status supports deduction where separately licensed infrastructure, resources, revenue, and expenditure establish c...
Agency reimbursement income follows contractual deposit-liability computation, while pending deposit collections do not constitute deemed-dividend loa...
Customs valuation of imported polyurethane-coated polyester...
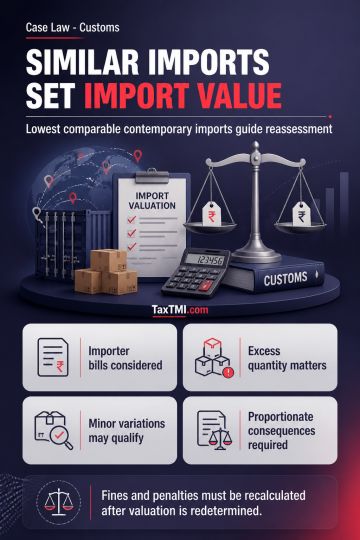
Customs valuation must use comparable contemporary imports, while confiscation fines and penalties require proportionate recalculation on reassessed value.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Customs valuation of imported polyurethane-coated polyester water-resistant fabrics must be redetermined under the Customs Valuation Rules, 2007 using comparable contemporary imports rather than an internal departmental instruction or the highest available comparable value. Bills of Entry submitted by the importer should be considered, with the lowest value of similar contemporary imports forming the basis for reassessment. Excess quantity and minor declaration variations may render goods liable to confiscation, even where thickness variations fall within the declared GSM range and no intent to evade duty is established. Redemption fine and penalty must remain proportionate to the importer's involvement and be recalculated by reference to the redetermined value.
Customs valuation of imported polyurethane-coated polyester water-resistant fabrics must be redetermined under the Customs Valuation Rules, 2007 using comparable contemporary imports rather than an internal departmental instruction or the highest available comparable value. Bills of Entry submitted by the importer should be considered, with the lowest value of similar contemporary imports forming the basis for reassessment. Excess quantity and minor declaration variations may render goods liable to confiscation, even where thickness variations fall within the declared GSM range and no intent to evade duty is established. Redemption fine and penalty must remain proportionate to the importer's involvement and be recalculated by reference to the redetermined value.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4894