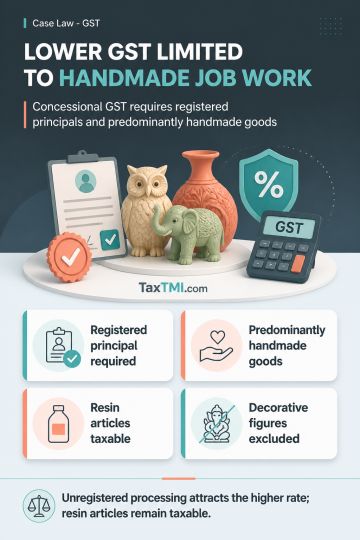
Handicraft job work receives concessional GST only for registered principals and predominantly handmade goods; commercial resin articles remain taxabl...
Reassessment disclosure requirements permit stated reasons without revealing information sources, but prior-taxation claims require full examination b...
Independent assessment discretion and corroborated electronic evidence determine validity of on-money additions and undisclosed-consideration assessme...
Merchant discount rate in credit-card transactions is a composite charge comprising the acquiring bank fee, issuing bank interchange fee and platform fee. Where service tax has been paid on the entire merchant discount rate, subsequent allocation of the interchange fee to the issuing bank does not create a separately taxable service. A further levy on that retained interchange fee would amount to double taxation, particularly where there is no revenue loss. Service-tax demands on interchange fee, along with consequential interest and penalties, were therefore unsustainable and set aside.
Merchant discount rate in credit-card transactions is a composite charge comprising the acquiring bank fee, issuing bank interchange fee and platform fee. Where service tax has been paid on the entire merchant discount rate, subsequent allocation of the interchange fee to the issuing bank does not create a separately taxable service. A further levy on that retained interchange fee would amount to double taxation, particularly where there is no revenue loss. Service-tax demands on interchange fee, along with consequential interest and penalties, were therefore unsustainable and set aside.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4935