GST refunds for cancelled air tickets remain available when passenger reimbursements defeat unjust enrichment and credit-note adjustment is unavailabl...
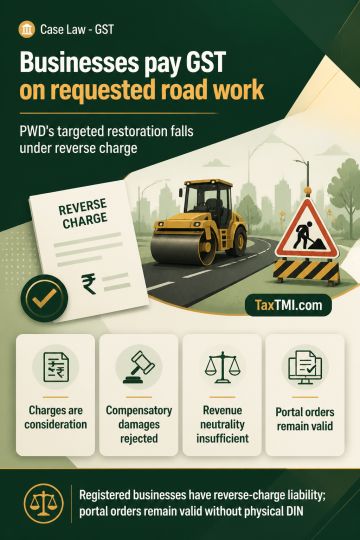
Request-driven road restoration attracts reverse-charge GST, not governmental-function treatment or compensatory-damages status for business recipient...
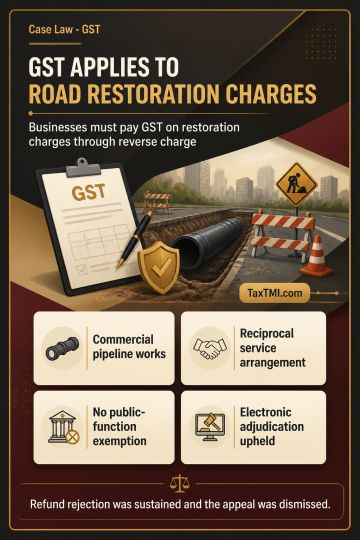
Road restoration charges for commercial pipeline works are taxable Government services, with reverse charge liability and no public-function exemption...
Section 48 requires capital gains to be computed using the consideration actually received or accruing, unless an applicable deeming provision permits substitution with fair market value. Redemption proceeds from non-cumulative preference shares therefore cannot be replaced by the price of equity shares in the same company, because the share classes carry different rights and no additional consideration was established. The provision for unquoted-share transfers and the rule for unascertainable consideration do not apply where redemption consideration is ascertainable. A claim for enhanced acquisition cost following capital reduction and consolidation requires factual verification of acquisition records, share identity, legal effect and cost allocation; it cannot be raised as a pure legal ground without an existing factual record.
Section 48 requires capital gains to be computed using the consideration actually received or accruing, unless an applicable deeming provision permits substitution with fair market value. Redemption proceeds from non-cumulative preference shares therefore cannot be replaced by the price of equity shares in the same company, because the share classes carry different rights and no additional consideration was established. The provision for unquoted-share transfers and the rule for unascertainable consideration do not apply where redemption consideration is ascertainable. A claim for enhanced acquisition cost following capital reduction and consolidation requires factual verification of acquisition records, share identity, legal effect and cost allocation; it cannot be raised as a pure legal ground without an existing factual record.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4931