Withdrawal of obsolete FEMA circulars streamlines rules on external commercial borrowings, non-resident bond investments, and money transfer sub-agent...
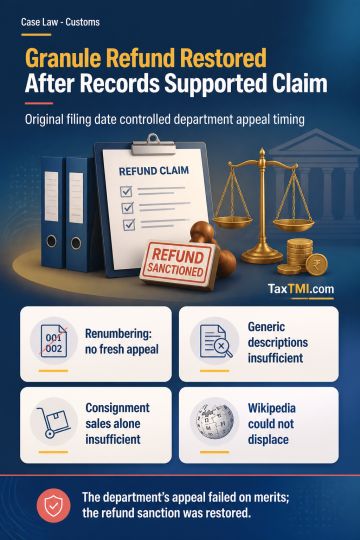
Departmental appeal limitation after call-book recall preserves original filing, while documented correlation supports SAD refund on imported granules...
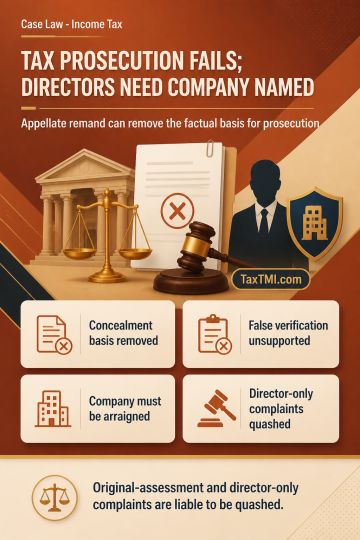
Income-tax prosecution fails when appellate remand removes its factual foundation; directors require company arraignment for vicarious criminal liabil...
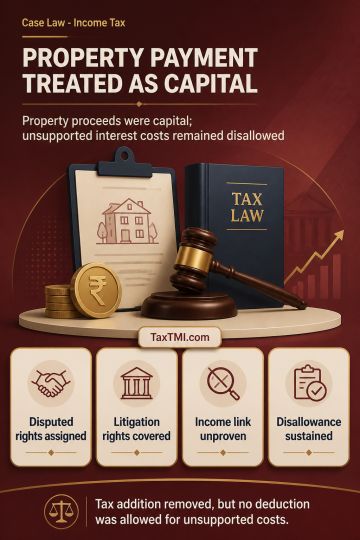
Capital character of assignment consideration prevents taxation as residuary income, while unsupported interest-related expenditure remains non-deduct...
Page of 4935
Press 'Enter' after typing page number.
1961 to 1980 of 98695 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Customs Broker licence proceedings require a factual basis for...
Customs Broker licence proceedings require accurate procedural facts before delay or natural-justice findings can justify setting aside regulatory action.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
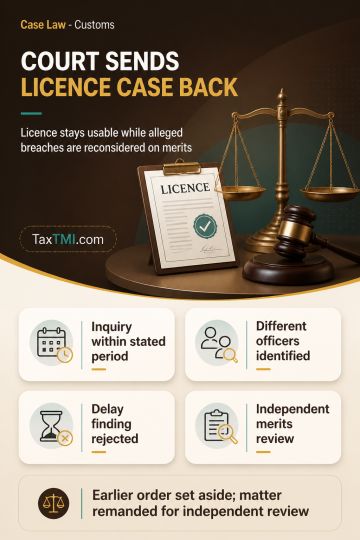
Customs Broker licence proceedings require a factual basis for findings of procedural prejudice. The High Court found that the Tribunal incorrectly treated the inquiry as inordinately delayed and wrongly assumed that the investigating and inquiry officers were the same, although the show cause notice and inquiry report were issued within the stated period by different officers. Because the Tribunal had not examined the alleged breaches of the Customs Brokers Licensing Regulations, 2018 on merits, its order was set aside and the matter remanded for an independent merits determination. The restored licence remains usable pending that decision.
Customs Broker licence proceedings require a factual basis for findings of procedural prejudice. The High Court found that the Tribunal incorrectly treated the inquiry as inordinately delayed and wrongly assumed that the investigating and inquiry officers were the same, although the show cause notice and inquiry report were issued within the stated period by different officers. Because the Tribunal had not examined the alleged breaches of the Customs Brokers Licensing Regulations, 2018 on merits, its order was set aside and the matter remanded for an independent merits determination. The restored licence remains usable pending that decision.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4935