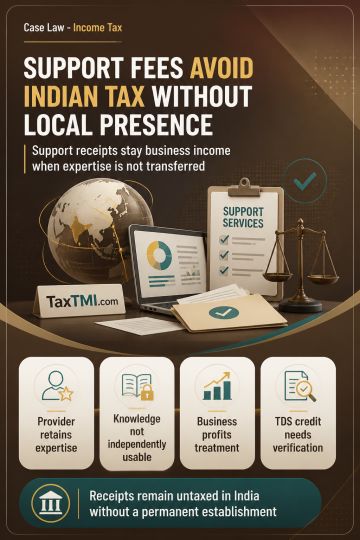
Make-available condition shields regional support-service receipts from Indian taxation where no independent capability or permanent establishment exi...
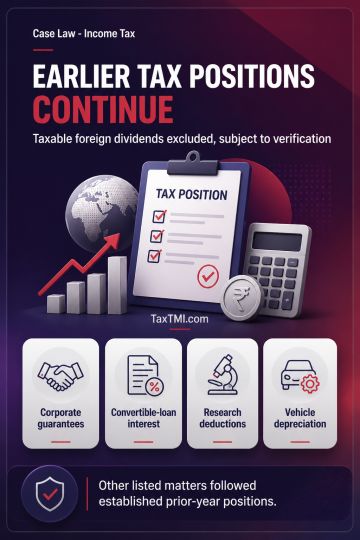
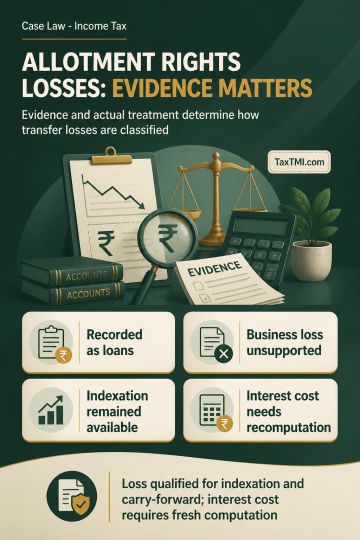
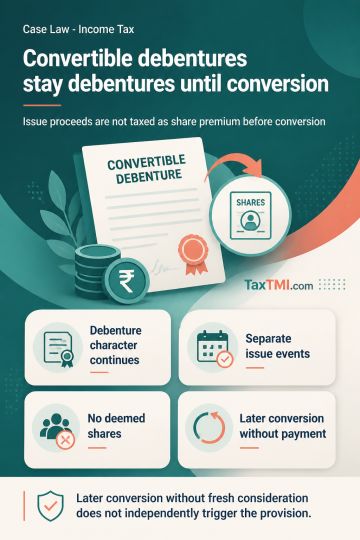
Transfer-pricing treatment of corporate guarantees and convertible loans followed prior-year consistency, with taxable foreign dividends excluded from...
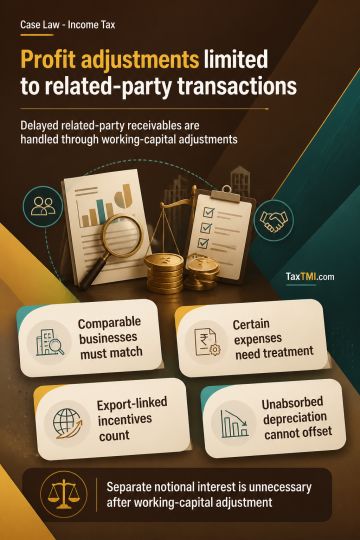
Transfer-pricing benchmarking confines adjustments to associated-enterprise transactions and integrates delayed receivables through TNMM working-capit...
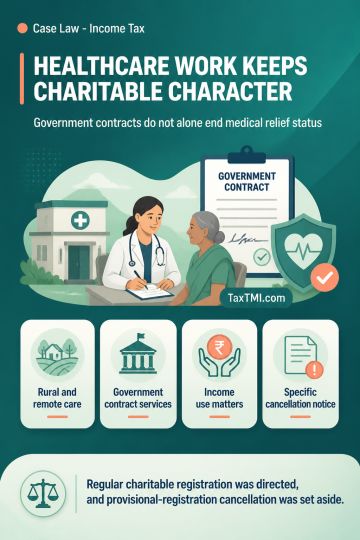
Medical relief status protects government-contracted mobile healthcare from commercial classification, while provisional registration cancellation req...
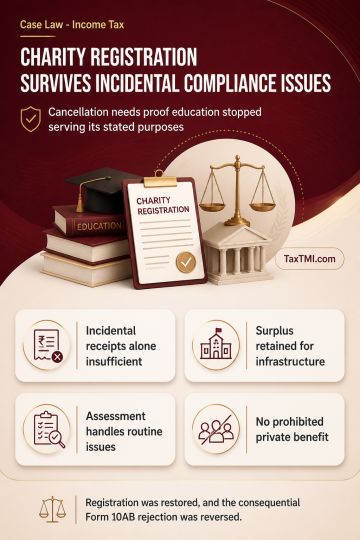
Charitable registration cancellation requires proof that educational activities abandoned their objects; incidental receipts and retained surplus are ...
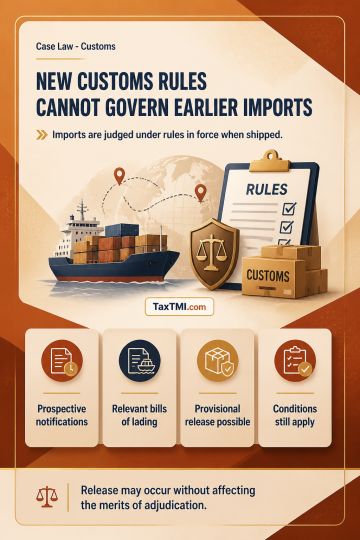
Prospective customs notification amendments cannot bar provisional release consideration for earlier imports when bills of lading predate their commen...
Customs Broker licence proceedings require a factual basis for...
Customs Broker licence proceedings require accurate procedural facts before delay or natural-justice findings can justify setting aside regulatory action.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Customs Broker licence proceedings require a factual basis for findings of procedural prejudice. The High Court found that the Tribunal incorrectly treated the inquiry as inordinately delayed and wrongly assumed that the investigating and inquiry officers were the same, although the show cause notice and inquiry report were issued within the stated period by different officers. Because the Tribunal had not examined the alleged breaches of the Customs Brokers Licensing Regulations, 2018 on merits, its order was set aside and the matter remanded for an independent merits determination. The restored licence remains usable pending that decision.
Customs Broker licence proceedings require a factual basis for findings of procedural prejudice. The High Court found that the Tribunal incorrectly treated the inquiry as inordinately delayed and wrongly assumed that the investigating and inquiry officers were the same, although the show cause notice and inquiry report were issued within the stated period by different officers. Because the Tribunal had not examined the alleged breaches of the Customs Brokers Licensing Regulations, 2018 on merits, its order was set aside and the matter remanded for an independent merits determination. The restored licence remains usable pending that decision.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4935