Blocked input tax credit for resort construction remains unavailable; interest follows actual utilisation, while delayed payment attracts statutory pe...
Duplicate PAN allocation requires record verification and deactivation reasons before assessment-related transactions can be attributed to an assessee...
Faceless assessment safeguards require requested personal hearings and adequate final show-cause response time, failing which reassessment is required...
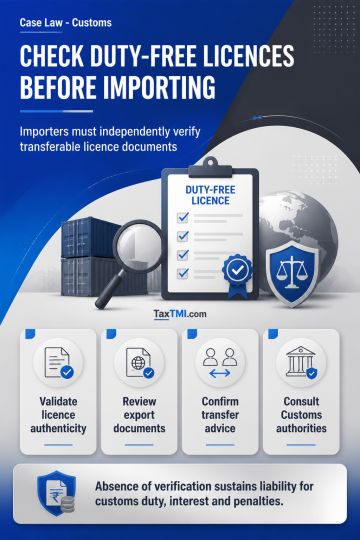
Transferee importers using duty-free DFIA licences linked to fabricated exports must independently verify licence authenticity, underlying export documents and transfer release advice. Verification solely through the DGFT website is insufficient. Purchase through intermediaries does not remove customs duty, interest or penalty exposure where the importer fails to undertake due diligence with licensing or Customs authorities regarding the issuing exporter and claimed exports. The stated Tribunal approach treats absence of such verification as sufficient to sustain liability for imports made under fraudulent transferable export incentive licences.
Transferee importers using duty-free DFIA licences linked to fabricated exports must independently verify licence authenticity, underlying export documents and transfer release advice. Verification solely through the DGFT website is insufficient. Purchase through intermediaries does not remove customs duty, interest or penalty exposure where the importer fails to undertake due diligence with licensing or Customs authorities regarding the issuing exporter and claimed exports. The stated Tribunal approach treats absence of such verification as sufficient to sustain liability for imports made under fraudulent transferable export incentive licences.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI