GST refunds for cancelled air tickets remain available when passenger reimbursements defeat unjust enrichment and credit-note adjustment is unavailabl...
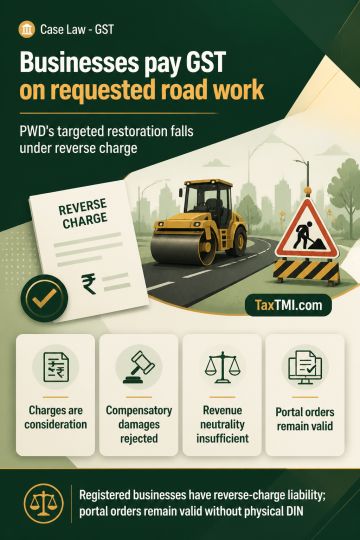
Request-driven road restoration attracts reverse-charge GST, not governmental-function treatment or compensatory-damages status for business recipient...
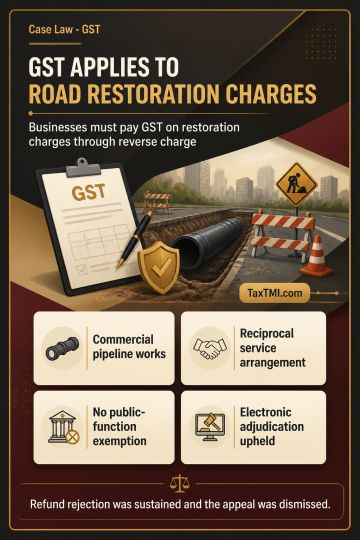
Road restoration charges for commercial pipeline works are taxable Government services, with reverse charge liability and no public-function exemption...
Regular bail was granted to an active partner accused of availing GST input tax credit through firms whose registrations had been cancelled from inception for non-existence or non-operation. Investigation had concluded and a complaint had been filed. Given the maximum prescribed punishment and the absence of reasonable grounds for continued custody, further detention was considered unwarranted. Bail was made subject to stipulated conditions, without affecting the Department's ability to take other measures available in law or the merits to be determined at trial.
Regular bail was granted to an active partner accused of availing GST input tax credit through firms whose registrations had been cancelled from inception for non-existence or non-operation. Investigation had concluded and a complaint had been filed. Given the maximum prescribed punishment and the absence of reasonable grounds for continued custody, further detention was considered unwarranted. Bail was made subject to stipulated conditions, without affecting the Department's ability to take other measures available in law or the merits to be determined at trial.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4931