Co-operative deduction eligibility excludes refund and commercial-bank interest, while qualifying co-operative investments require entity-wise verific...
Enhanced tax rate on surrendered unexplained income applies prospectively, while cash-deposit telescoping requires verification of available surrender...
Customs Broker licence proceedings require accurate procedural facts before delay or natural-justice findings can justify setting aside regulatory act...
Provisional assessment finalisation must precede export duty recovery, while redemption fine fails for goods already exported and unavailable for conf...
Page of 4894
Press 'Enter' after typing page number.
1881 to 1900 of 97867 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
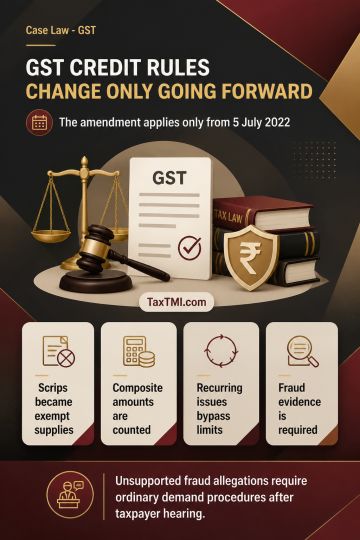
CBIC monetary-limit instructions bind central tax officers, not the Tribunal. Where a composite order covers multiple demands, the total amount involved must be considered; appeals concerning recurring issues or statutory interpretation fall outside the monetary-limit bar. Duty credit scrips became exempt supplies in 2017, but their exclusion from aggregate exempt supplies for proportionate input tax credit reversal applies prospectively from 5 July 2022. The later amendment conferred a prospective benefit and did not retrospectively alter earlier reversal obligations. Extended demand proceedings require material showing fraud, wilful misstatement or deliberate suppression intended to evade tax; mere non-declaration is insufficient. Absent such material, tax liability must be determined under the ordinary demand procedure after hearing the taxpayer.
CBIC monetary-limit instructions bind central tax officers, not the Tribunal. Where a composite order covers multiple demands, the total amount involved must be considered; appeals concerning recurring issues or statutory interpretation fall outside the monetary-limit bar. Duty credit scrips became exempt supplies in 2017, but their exclusion from aggregate exempt supplies for proportionate input tax credit reversal applies prospectively from 5 July 2022. The later amendment conferred a prospective benefit and did not retrospectively alter earlier reversal obligations. Extended demand proceedings require material showing fraud, wilful misstatement or deliberate suppression intended to evade tax; mere non-declaration is insufficient. Absent such material, tax liability must be determined under the ordinary demand procedure after hearing the taxpayer.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4894