Intermediary service classification fails where overseas admission facilitation is supplied independently, preserving export treatment and small-provi...
Satellite transponder bandwidth is telecommunication, not Business Support Service; foreign non-telegraph providers triggered no service tax liability...
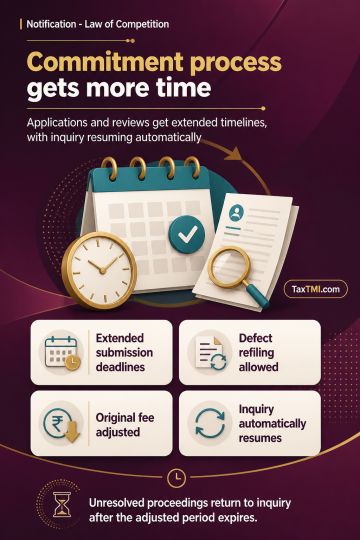
Commitment proceedings gain extended timelines, structured defect refiling, and automatic resumption of inquiry after the adjusted completion period e...
Centralised assessment transfer becomes unwarranted once the searched person's assessment is complete, requiring restoration to the appropriate charge...
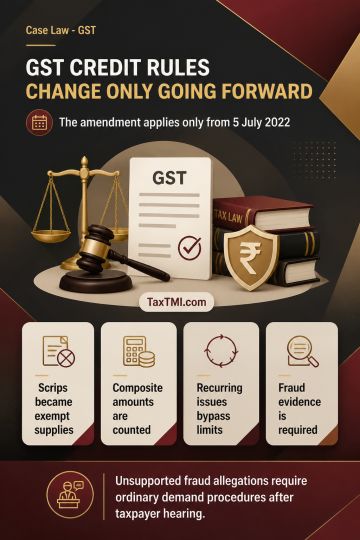
CBIC monetary-limit instructions bind central tax officers, not the Tribunal. Where a composite order covers multiple demands, the total amount involved must be considered; appeals concerning recurring issues or statutory interpretation fall outside the monetary-limit bar. Duty credit scrips became exempt supplies in 2017, but their exclusion from aggregate exempt supplies for proportionate input tax credit reversal applies prospectively from 5 July 2022. The later amendment conferred a prospective benefit and did not retrospectively alter earlier reversal obligations. Extended demand proceedings require material showing fraud, wilful misstatement or deliberate suppression intended to evade tax; mere non-declaration is insufficient. Absent such material, tax liability must be determined under the ordinary demand procedure after hearing the taxpayer.
CBIC monetary-limit instructions bind central tax officers, not the Tribunal. Where a composite order covers multiple demands, the total amount involved must be considered; appeals concerning recurring issues or statutory interpretation fall outside the monetary-limit bar. Duty credit scrips became exempt supplies in 2017, but their exclusion from aggregate exempt supplies for proportionate input tax credit reversal applies prospectively from 5 July 2022. The later amendment conferred a prospective benefit and did not retrospectively alter earlier reversal obligations. Extended demand proceedings require material showing fraud, wilful misstatement or deliberate suppression intended to evade tax; mere non-declaration is insufficient. Absent such material, tax liability must be determined under the ordinary demand procedure after hearing the taxpayer.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4894