Higher depreciation for qualifying commercial vehicles, exempt-income disallowance, research deduction verification, and club-expense treatment clarif...
Charitable registration renewal cannot become an assessment of receipts, profitability or annual exemption compliance, requiring renewal and donation ...
AMP expenditure for own business is not an international transaction without an associated-enterprise arrangement, eliminating transfer pricing adjust...
Customs valuation must use comparable contemporary imports, while confiscation fines and penalties require proportionate recalculation on reassessed v...
Depositor-protection proceedings prevail over corporate insolvency, while liquidators may recover chit receivables using copies of seized company reco...
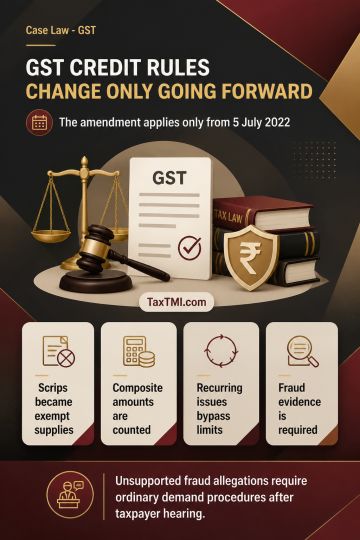
CBIC monetary-limit instructions bind central tax officers, not the Tribunal. Where a composite order covers multiple demands, the total amount involved must be considered; appeals concerning recurring issues or statutory interpretation fall outside the monetary-limit bar. Duty credit scrips became exempt supplies in 2017, but their exclusion from aggregate exempt supplies for proportionate input tax credit reversal applies prospectively from 5 July 2022. The later amendment conferred a prospective benefit and did not retrospectively alter earlier reversal obligations. Extended demand proceedings require material showing fraud, wilful misstatement or deliberate suppression intended to evade tax; mere non-declaration is insufficient. Absent such material, tax liability must be determined under the ordinary demand procedure after hearing the taxpayer.
CBIC monetary-limit instructions bind central tax officers, not the Tribunal. Where a composite order covers multiple demands, the total amount involved must be considered; appeals concerning recurring issues or statutory interpretation fall outside the monetary-limit bar. Duty credit scrips became exempt supplies in 2017, but their exclusion from aggregate exempt supplies for proportionate input tax credit reversal applies prospectively from 5 July 2022. The later amendment conferred a prospective benefit and did not retrospectively alter earlier reversal obligations. Extended demand proceedings require material showing fraud, wilful misstatement or deliberate suppression intended to evade tax; mere non-declaration is insufficient. Absent such material, tax liability must be determined under the ordinary demand procedure after hearing the taxpayer.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4894