ODR arbitration participation remains mandatory after failed conciliation, while jurisdictional and maintainability objections stay available before t...
Transparency in technical bid evaluation requires disclosed standards and recorded reasons; opaque scoring invalidated tender awards and required fres...
Automated export obligation extensions remove separate regional applications after committee approval for Advance Authorisation and EPCG authorisation...
International cargo transhipment through Indian ports continues with Customs-controlled storage, re-export safeguards, and coordinated multi-station m...
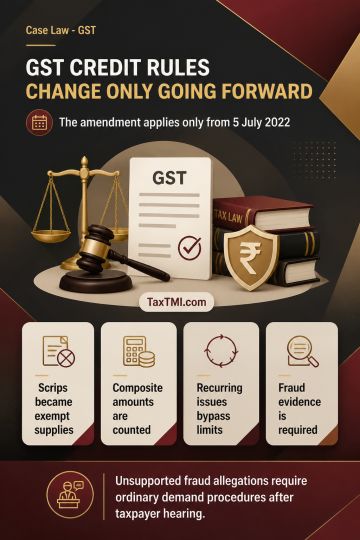
CBIC monetary-limit instructions bind central tax officers, not the Tribunal. Where a composite order covers multiple demands, the total amount involved must be considered; appeals concerning recurring issues or statutory interpretation fall outside the monetary-limit bar. Duty credit scrips became exempt supplies in 2017, but their exclusion from aggregate exempt supplies for proportionate input tax credit reversal applies prospectively from 5 July 2022. The later amendment conferred a prospective benefit and did not retrospectively alter earlier reversal obligations. Extended demand proceedings require material showing fraud, wilful misstatement or deliberate suppression intended to evade tax; mere non-declaration is insufficient. Absent such material, tax liability must be determined under the ordinary demand procedure after hearing the taxpayer.
CBIC monetary-limit instructions bind central tax officers, not the Tribunal. Where a composite order covers multiple demands, the total amount involved must be considered; appeals concerning recurring issues or statutory interpretation fall outside the monetary-limit bar. Duty credit scrips became exempt supplies in 2017, but their exclusion from aggregate exempt supplies for proportionate input tax credit reversal applies prospectively from 5 July 2022. The later amendment conferred a prospective benefit and did not retrospectively alter earlier reversal obligations. Extended demand proceedings require material showing fraud, wilful misstatement or deliberate suppression intended to evade tax; mere non-declaration is insufficient. Absent such material, tax liability must be determined under the ordinary demand procedure after hearing the taxpayer.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4897