Embezzlement losses in charitable institutions remain allowable when misappropriation is established, irrecoverable, and not a specified-person benefi...
National long-distance undertaking status supports deduction where separately licensed infrastructure, resources, revenue, and expenditure establish c...
Agency reimbursement income follows contractual deposit-liability computation, while pending deposit collections do not constitute deemed-dividend loa...
Membership-consent thresholds for oppression petitions are satisfied by unchallenged voter-list consents, while unsupported forgery claims require pro...
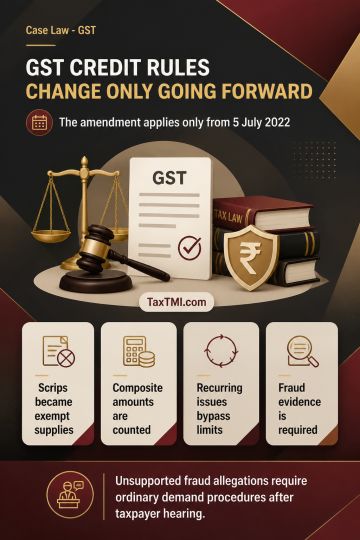
CBIC monetary-limit instructions bind central tax officers, not the Tribunal. Where a composite order covers multiple demands, the total amount involved must be considered; appeals concerning recurring issues or statutory interpretation fall outside the monetary-limit bar. Duty credit scrips became exempt supplies in 2017, but their exclusion from aggregate exempt supplies for proportionate input tax credit reversal applies prospectively from 5 July 2022. The later amendment conferred a prospective benefit and did not retrospectively alter earlier reversal obligations. Extended demand proceedings require material showing fraud, wilful misstatement or deliberate suppression intended to evade tax; mere non-declaration is insufficient. Absent such material, tax liability must be determined under the ordinary demand procedure after hearing the taxpayer.
CBIC monetary-limit instructions bind central tax officers, not the Tribunal. Where a composite order covers multiple demands, the total amount involved must be considered; appeals concerning recurring issues or statutory interpretation fall outside the monetary-limit bar. Duty credit scrips became exempt supplies in 2017, but their exclusion from aggregate exempt supplies for proportionate input tax credit reversal applies prospectively from 5 July 2022. The later amendment conferred a prospective benefit and did not retrospectively alter earlier reversal obligations. Extended demand proceedings require material showing fraud, wilful misstatement or deliberate suppression intended to evade tax; mere non-declaration is insufficient. Absent such material, tax liability must be determined under the ordinary demand procedure after hearing the taxpayer.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881