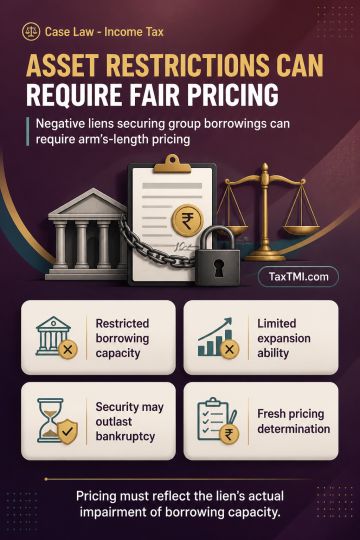
Negative liens over operating assets can constitute international transactions requiring arm's-length pricing reflecting restricted borrowing and expa...
Cross-examination rights in Customs Broker revocation inquiries require witness examination; procedural denial may be cured through fresh adjudication...
Governmental authority status supports construction-service exemption, while pre-cutoff contract and stamp-duty compliance requires verification on re...
Automated Free Sale and Commerce Certificates enable paperless processing while retaining risk-based manual verification for selected exporter applica...
Revision of block assessment under section 263 could not revisit additions concerning claimed unaccounted expenditure, asset investments and petrol-pump income after those additions had been adjudicated in appellate proceedings and the Tribunal's decision had attained finality following dismissal of Revenue appeals. Revisionary proceedings on those matters were therefore set aside. Regarding tanker acquisition and operating income, concurrent factual findings after record verification established no material showing unaccounted income. With no legal infirmity in those findings, deletion of the tanker-related addition was sustained and the Revenue's appeals were dismissed.
Revision of block assessment under section 263 could not revisit additions concerning claimed unaccounted expenditure, asset investments and petrol-pump income after those additions had been adjudicated in appellate proceedings and the Tribunal's decision had attained finality following dismissal of Revenue appeals. Revisionary proceedings on those matters were therefore set aside. Regarding tanker acquisition and operating income, concurrent factual findings after record verification established no material showing unaccounted income. With no legal infirmity in those findings, deletion of the tanker-related addition was sustained and the Revenue's appeals were dismissed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4934