Transfer-pricing treatment of ITeS margins excludes pass-through tax recoveries and separate delayed-receivables interest after working-capital adjust...
Capacity-utilisation adjustments under TNMM can neutralise substantiated COVID-related idle costs where underutilisation materially affects profitabil...
TNMM functional comparability requires excluding rice manufacturers from a pure Basmati rice trader's benchmark and recognising operating export recei...
Working-capital adjustment subsumes delayed-receivable effects in TNMM benchmarking of captive software-development services, avoiding separate notion...
Transfer-pricing comparability requires exclusion of financially illogical super-profit comparables and correction of unsupported annual-report and ma...
Charitable character assessment preserves Section 80G approval despite inclusive spiritual teachings and incidental religious expenditure within the s...
Penalty proceedings for cash-loan acceptance require assessment proceedings and recorded Assessing Officer satisfaction; absent these, the proceedings...
Service permanent establishment analysis under the India-USA...
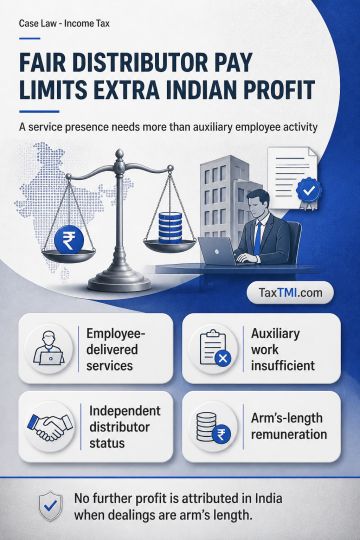
Service permanent establishment requires non-auxiliary services, while arm's-length distributor remuneration precludes further profit attribution in India.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Service permanent establishment analysis under the India-USA DTAA requires services to be furnished through employees or other personnel and excludes services covered as royalties or fees for included services. Stewardship, oversight and other auxiliary activities do not establish a service PE unless the nature of training, administrative, news-gathering or sales-support functions is shown to exceed auxiliary activity or to constitute technical or consultancy services. A distributor operating independently on a principal-to-principal basis, without authority to conclude contracts, maintain delivery stock or habitually secure orders, does not constitute a dependent agent PE. Where intercompany dealings are at arm's length, no further profit is attributable to an alleged PE.
Service permanent establishment analysis under the India-USA DTAA requires services to be furnished through employees or other personnel and excludes services covered as royalties or fees for included services. Stewardship, oversight and other auxiliary activities do not establish a service PE unless the nature of training, administrative, news-gathering or sales-support functions is shown to exceed auxiliary activity or to constitute technical or consultancy services. A distributor operating independently on a principal-to-principal basis, without authority to conclude contracts, maintain delivery stock or habitually secure orders, does not constitute a dependent agent PE. Where intercompany dealings are at arm's length, no further profit is attributable to an alleged PE.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4937