Belated Form 10B filing during Covid-19 cannot defeat charitable exemption where genuine hardship warrants condonation and substantial justice prevail...
Limitation for consequential assessments runs from prescribed authority receipt, while verified purchases cannot be disallowed merely for unanswered s...
Page of 4894
Press 'Enter' after typing page number.
1821 to 1840 of 97867 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
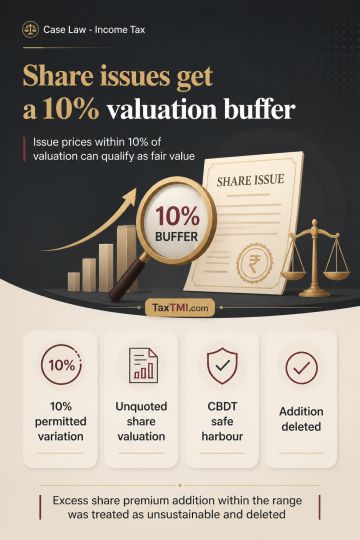
Section 56(2)(viib) share-premium additions may not arise where the issue price of unquoted shares exceeds the Rule 11UA value by no more than 10%. The CBDT's curative safe-harbour amendment treats the issue price within that permissible variation as fair market value. Applying this safe harbour, an addition for excess share premium within the 10% range was treated as unsustainable and deleted.
Section 56(2)(viib) share-premium additions may not arise where the issue price of unquoted shares exceeds the Rule 11UA value by no more than 10%. The CBDT's curative safe-harbour amendment treats the issue price within that permissible variation as fair market value. Applying this safe harbour, an addition for excess share premium within the 10% range was treated as unsustainable and deleted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4894