Customs exemptions cover photovoltaic assembly machinery and PVF backsheets, while fully declared cleared imports may avoid confiscation and penalties...
Specific tariff classification for LCD devices overrides treatment as electricity-meter parts, defeating differential duty, extended limitation, and p...
Stayed disciplinary punishment does not establish unfitness for insolvency professional registration; reconsideration must disregard mere pendency of ...
Indirect corporate control can create related-party status, excluding financial creditors from Committee of Creditors representation, participation an...
Scientific research association approval requires continuing SIRO status, annual donation reporting, and donor certificates for the approved foundatio...
Scientific research institution approval is conditional on SIRO recognition, annual donation reporting, donor certification, and prescribed compliance...
SaaS subscription receipts from Indian customers for a standard,...
Make-available condition excludes standard SaaS subscription receipts where customers receive no independently usable technical knowledge after subscription expiry.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
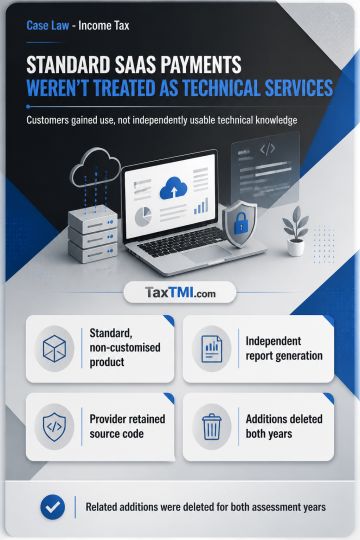
SaaS subscription receipts from Indian customers for a standard, non-customised software development kit and dashboard facility did not constitute fees for included services under Article 12(4) of the India-USA DTAA. Customers integrated the product and generated reports independently, while the provider retained its algorithms, source code and processes; use of technology did not make technical knowledge available for independent post-subscription use. Incidental account management, support and demonstrations did not change the transaction's predominant automated character. The related additions were deleted for both assessment years. Tax deducted at source credit required Assessing Officer verification before grant, and the challenge to penalty initiation for under-reporting was premature.
SaaS subscription receipts from Indian customers for a standard, non-customised software development kit and dashboard facility did not constitute fees for included services under Article 12(4) of the India-USA DTAA. Customers integrated the product and generated reports independently, while the provider retained its algorithms, source code and processes; use of technology did not make technical knowledge available for independent post-subscription use. Incidental account management, support and demonstrations did not change the transaction's predominant automated character. The related additions were deleted for both assessment years. Tax deducted at source credit required Assessing Officer verification before grant, and the challenge to penalty initiation for under-reporting was premature.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4883