Assessing Officer jurisdiction after statutory transfer invalidates reassessment notices issued by transferor officers and nullifies resulting proceed...
Consequential appeal-effect orders must implement rectification deleting working-capital adjustments and reconsider the resulting arm's-length range c...
Discounted cash flow valuation protects share premium where projections are reasonable, while audited book expenses defeat unexplained-expenditure add...
Section 54 construction relief survives pre-transfer commencement when completion occurs within the statutory period, excluding ineligible spouse-owne...
Fraud classification show-cause notices founded on inconclusive forensic audit material cannot sustain action, permitting fresh proceedings on conclus...
Page of 4888
Press 'Enter' after typing page number.
381 to 400 of 97750 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
SaaS subscription receipts from Indian customers for a standard,...
Make-available condition excludes standard SaaS subscription receipts where customers receive no independently usable technical knowledge after subscription expiry.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
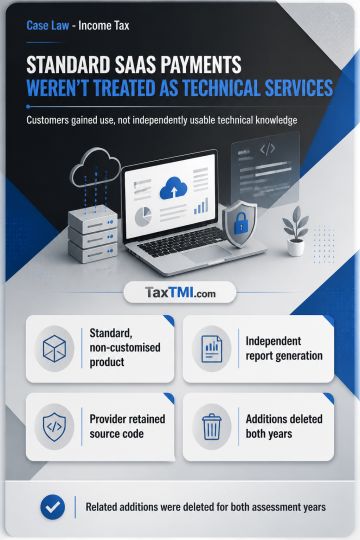
SaaS subscription receipts from Indian customers for a standard, non-customised software development kit and dashboard facility did not constitute fees for included services under Article 12(4) of the India-USA DTAA. Customers integrated the product and generated reports independently, while the provider retained its algorithms, source code and processes; use of technology did not make technical knowledge available for independent post-subscription use. Incidental account management, support and demonstrations did not change the transaction's predominant automated character. The related additions were deleted for both assessment years. Tax deducted at source credit required Assessing Officer verification before grant, and the challenge to penalty initiation for under-reporting was premature.
SaaS subscription receipts from Indian customers for a standard, non-customised software development kit and dashboard facility did not constitute fees for included services under Article 12(4) of the India-USA DTAA. Customers integrated the product and generated reports independently, while the provider retained its algorithms, source code and processes; use of technology did not make technical knowledge available for independent post-subscription use. Incidental account management, support and demonstrations did not change the transaction's predominant automated character. The related additions were deleted for both assessment years. Tax deducted at source credit required Assessing Officer verification before grant, and the challenge to penalty initiation for under-reporting was premature.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4888