Money-laundering judgment timing requires awaiting the scheduled-offence decision despite continuation of the underlying trial where outcomes directly...
Accredited investor eligibility expands through securities-market exposure, while alternative investment fund disputes require prescribed resolution a...
Customs Assessment Portal centralises classification and valuation guidance to support consistent, transparent and informed compliance across stakehol...
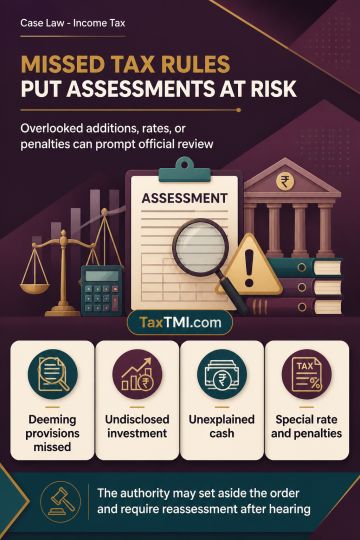
Revision of an assessment is warranted where the Assessing Officer fails to apply the statutory deeming provisions to additions for undisclosed investment and unexplained cash, omits the applicable special tax rate, and does not consider penalty proceedings. An order is erroneous when based on incorrect facts or law, made without due application of mind, or contrary to natural justice. It is prejudicial to revenue where lawful tax is not realised. The revisional authority may set aside such an assessment, direct further inquiry, and require reassessment under the correct provisions after providing an opportunity of being heard.
Revision of an assessment is warranted where the Assessing Officer fails to apply the statutory deeming provisions to additions for undisclosed investment and unexplained cash, omits the applicable special tax rate, and does not consider penalty proceedings. An order is erroneous when based on incorrect facts or law, made without due application of mind, or contrary to natural justice. It is prejudicial to revenue where lawful tax is not realised. The revisional authority may set aside such an assessment, direct further inquiry, and require reassessment under the correct provisions after providing an opportunity of being heard.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4931