Penny-stock additions require transaction-specific evidence; general investigation material alone cannot establish undisclosed income or accommodation...
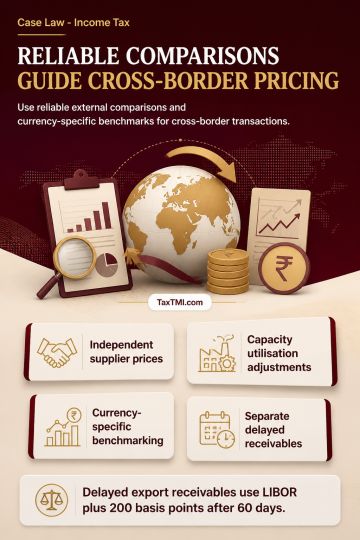
Transfer pricing comparability prioritises reliable external CUPs and foreign-currency LIBOR benchmarks for exports, borrowings and delayed receivable...
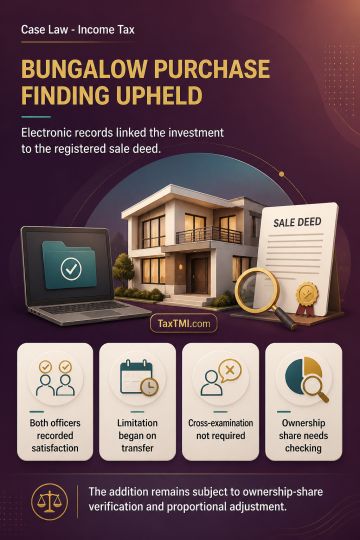
Section 153C satisfaction and seized electronic records sustained unexplained-investment addition, subject to proportionate ownership-share verificati...
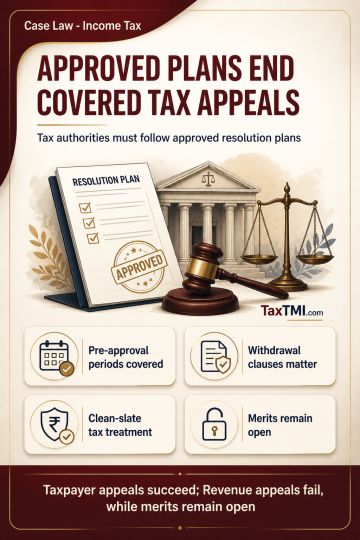
An approved resolution plan binds governmental and statutory authorities and operates on a clean-slate basis for tax proceedings relating to pre-approval periods. Where plan clauses expressly extinguish and require withdrawal of pending tax proceedings concerning the corporate debtor, affiliates and subsidiaries, income-tax jurisdiction cannot be exercised inconsistently with the plan. A legal plea based on subsequent undisputed approval of the plan may be admitted in appellate proceedings where it goes to the root of the matter and requires no fresh factual enquiry. Income-tax appeals for the relevant pre-approval assessment years cannot continue; the taxpayer's appeals succeed on this preliminary issue, the Revenue's appeals fail, and merits issues remain open.
An approved resolution plan binds governmental and statutory authorities and operates on a clean-slate basis for tax proceedings relating to pre-approval periods. Where plan clauses expressly extinguish and require withdrawal of pending tax proceedings concerning the corporate debtor, affiliates and subsidiaries, income-tax jurisdiction cannot be exercised inconsistently with the plan. A legal plea based on subsequent undisputed approval of the plan may be admitted in appellate proceedings where it goes to the root of the matter and requires no fresh factual enquiry. Income-tax appeals for the relevant pre-approval assessment years cannot continue; the taxpayer's appeals succeed on this preliminary issue, the Revenue's appeals fail, and merits issues remain open.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4899