Loading...

⚠ ✕
❮ Top
☎ Help
☰
×

By creating an account you can:

Logo TaxTMI
Call Us / Help / Feedback✕

Contact Us At :

✉ E-mail: [email protected]

✆ Call / WhatsApp at: +91 99117 96707

For more information, Check Contact Us

FAQs :

To know Frequently Asked Questions, Check FAQs

Most Asked Video Tutorials :

For more tutorials, Check Video Tutorials

Submit Feedback/Suggestion :

Email :
Please provide your email address so we can follow up on your feedback.
Category :
Description :
Min 15 characters 0/2000
Make Most of Text Search ✕
  1. Checkout this video tutorial: How to search effectively on TaxTMI.
  2. Put words in double quotes for exact word search, eg: "income tax"
  3. Avoid noise words such as : 'and, of, the, a'
  4. Sort by Relevance to get the most relevant document.
  5. Press Enter to add multiple terms/multiple phrases, and then click on Search to Search.
  6. Text Search
  7. The system will try to fetch results that contains ALL your words.
  8. Once you add keywords, you'll see a new 'Search In' filter that makes your results even more precise.
  9. Text Search
╳
Add to...
You have not created any category. Kindly create one to bookmark this item!
✕
Create New Category
Hide
Title :
Description :
❮❮ Hide
❮ Default View
Expand ❯❯
Close ✕
🔎 Filters / Advanced Search ❯
TEXT

Press 'Enter' to add multiple search terms. Rules for Better Search

Search In
Main Text + AI Text ❯
  • Main Text
  • Main Text + AI Text
  • AI Text
Law:
---- All Laws---- ❯
  • ---- All Laws----
  • Income Tax
  • Direct Taxes
  • Benami Property
  • Central GST Laws
  • SGST - State GST Laws
  • Customs
  • FTP - Foreign Trade Policy
  • SEZ - Special Economic Zone
  • FEMA - Foreign Exchange Management
  • Companies Law
  • SEBI - Securities & Exchange Board of India
  • IBC - Insolvency and Bankruptcy
  • Law of Competition
  • PMLA - Money-Laundering
  • Indian Laws
  • Bill / Finance Bills
  • Wealth Tax
  • Service Tax
  • Central Excise
  • VAT / Sales Tax
Month:
---- All Months ---- ❯
  • ---- All Months ----
  • January
  • February
  • March
  • April
  • May
  • June
  • July
  • August
  • September
  • October
  • November
  • December
Year:
---- All Years ---- ❯
  • ---- All Years ----
  • 2026
  • 2025
  • 2024
  • 2023
  • 2022
  • 2021
  • 2020
  • 2019
  • 2018
  • 2017
  • 2016
  • 2015
  • 2014
  • 2013
  • 2012
  • 2011
Sort By: ?
In Sort By 'Default', exact matches for text search are shown at the top, followed by the remaining results in their regular order.
Relevance Default Date
☰   Show Results ❯
    Technical expert evidence in customs classification must receive reasoned evaluation; denial of concession was quashed and remanded.
    Burden of proof for reclassification prevents lead-bearing powder from being treated as lead waste and scrap without conclusive scientific evidence.
    NBFC prudential-norm breaches may support oppression and mismanagement claims when combined with related-party dealings and governance failures.
    Operational debt from consortium supply advances survives where no genuine pre-existing dispute predates the insolvency demand notice.
    Nexus to coaching service excludes separately supplied study material, hostel, mess and unrelated ancillary collections from taxable value.
    Consistent Revenue positions on export status require CENVAT refunds for qualifying foreign-recipient business services supplied from India.
    Comparable-service valuation requires similarly placed recipients; new-buyer sale prices cannot value redevelopment allotments to existing occupants.
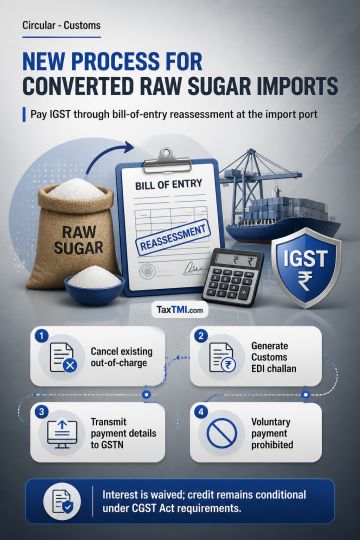
    IGST payment on converted raw sugar imports requires bill-of-entry reassessment, Customs EDI payment, and GSTN-linked credit processing.
    E-way bill reuse allegations require cogent evidence; suspicion alone cannot establish GST contravention or intention to evade tax.
    E-way bill reuse allegations require independent proof; suspicion alone cannot sustain goods detention or tax-evasion penalties.
    Psyllium seed classification turns on condition at supply, making dried stored seeds taxable rather than GST-exempt fresh goods.
    Tax residency relief for Indian seafarers during COVID-19 was sought through a challenge to administrative guidance.
    Section 260A Fact-Finding Limits Bar Reassessment of Book Rejection, Income Estimates, and Fee-Refund Relief on Appeal
    Share-capital issue expenses include Registrar fees, allowing preliminary-expenditure amortisation where shares are issued to a holding company.
    Decoding seized numerical entries requires reasoned evidentiary support; unsupported multipliers fail, while duplicate taxation and financial incapaci...
    Revisionary jurisdiction cannot replace an Assessing Officer's considered view after full disclosure and examination during assessment.
    Revision for alleged lack of inquiry fails where assessment records show inquiries, application of mind, and no identified defects.
    Interest on excess self-assessment tax refunds runs from payment where appellate relief reduces tax ultimately chargeable.
    Advance-tax appeal admission requires examination of claimed absence of taxable income before dismissal or remand
    Tax-motivated capital loss remains allowable where share transactions are genuine and lack evidence of an artificial arrangement.
❮
❯
❯❯
Maximize Maximize Maximize
0 / 200
Expand Note
Add to Folder

No Folders have been created

+

Are you sure you want to delete "My most important" ?

NOTE:

Highlights
Showing Results for :
Reset Filters
Results Found:
Show All Summaries Hide All Summaries

Highlights

Back

All Highlights

Showing Results for :
Reset Filters
No Records Found

Highlights

Back

All Highlights

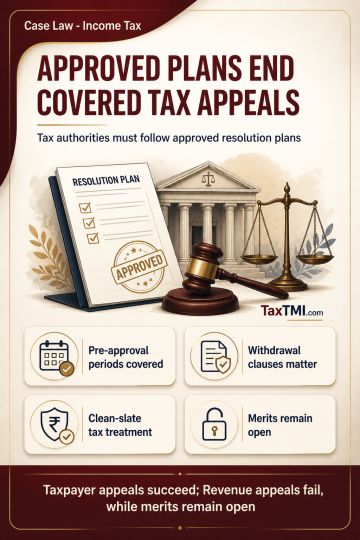
An approved resolution plan binds governmental and statutory...

Approved resolution plans bind tax authorities and extinguish pre-approval tax appeals where plan terms require withdrawal of proceedings.

Contents
Summary
Note

Note

-

Bookmark

Print

Print

Income Tax August 19, 2026 Case Laws AT
An approved resolution plan binds governmental and statutory authorities and operates on a clean-slate basis for tax proceedings relating to pre-approval periods. Where plan clauses expressly extinguish and require withdrawal of pending tax proceedings concerning the corporate debtor, affiliates and subsidiaries, income-tax jurisdiction cannot be exercised inconsistently with the plan. A legal plea based on subsequent undisputed approval of the plan may be admitted in appellate proceedings where it goes to the root of the matter and requires no fresh factual enquiry. Income-tax appeals for the relevant pre-approval assessment years cannot continue; the taxpayer's appeals succeed on this preliminary issue, the Revenue's appeals fail, and merits issues remain open.

Topics

Acts Income Tax