Section 80JJAA employee-cost deduction allowed for deployed staff but barred against transfer-pricing income enhancement, with pricing issues remanded...
Transfer-pricing methodology protects commercially genuine associated-enterprise payments, while pre-2016 secondary adjustments and related notional i...
Negative liens over operating assets can constitute international transactions requiring arm's-length pricing reflecting restricted borrowing and expa...
Cross-examination rights in Customs Broker revocation inquiries require witness examination; procedural denial may be cured through fresh adjudication...
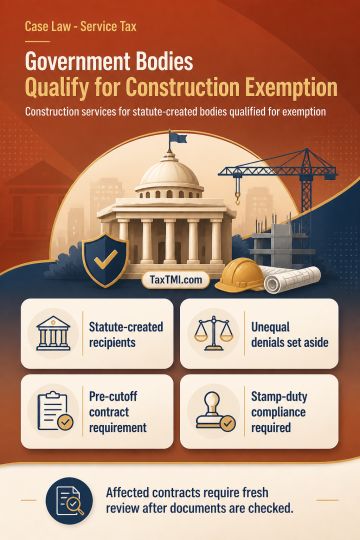
Governmental authority status supports construction-service exemption, while pre-cutoff contract and stamp-duty compliance requires verification on re...
An approved resolution plan binds governmental and statutory authorities and operates on a clean-slate basis for tax proceedings relating to pre-approval periods. Where plan clauses expressly extinguish and require withdrawal of pending tax proceedings concerning the corporate debtor, affiliates and subsidiaries, income-tax jurisdiction cannot be exercised inconsistently with the plan. A legal plea based on subsequent undisputed approval of the plan may be admitted in appellate proceedings where it goes to the root of the matter and requires no fresh factual enquiry. Income-tax appeals for the relevant pre-approval assessment years cannot continue; the taxpayer's appeals succeed on this preliminary issue, the Revenue's appeals fail, and merits issues remain open.
An approved resolution plan binds governmental and statutory authorities and operates on a clean-slate basis for tax proceedings relating to pre-approval periods. Where plan clauses expressly extinguish and require withdrawal of pending tax proceedings concerning the corporate debtor, affiliates and subsidiaries, income-tax jurisdiction cannot be exercised inconsistently with the plan. A legal plea based on subsequent undisputed approval of the plan may be admitted in appellate proceedings where it goes to the root of the matter and requires no fresh factual enquiry. Income-tax appeals for the relevant pre-approval assessment years cannot continue; the taxpayer's appeals succeed on this preliminary issue, the Revenue's appeals fail, and merits issues remain open.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4902