Infrastructure-development deduction remains available to EPC contractors when substantive statutory conditions outweigh contractor labels in agreemen...
Explained Investment Sources: documented gifts and traceable salary savings supported deletion of additions for property and mutual-fund SIP investmen...
Internal comparable pricing supports arm's-length interest on compulsorily convertible debentures, preventing their recharacterisation as equity for t...
Nominee director protection shields independent financial-institution appointees from criminal liability where they lack involvement in deposit defaul...
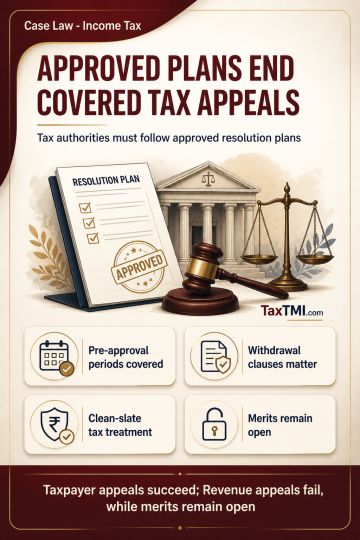
An approved resolution plan binds governmental and statutory authorities and operates on a clean-slate basis for tax proceedings relating to pre-approval periods. Where plan clauses expressly extinguish and require withdrawal of pending tax proceedings concerning the corporate debtor, affiliates and subsidiaries, income-tax jurisdiction cannot be exercised inconsistently with the plan. A legal plea based on subsequent undisputed approval of the plan may be admitted in appellate proceedings where it goes to the root of the matter and requires no fresh factual enquiry. Income-tax appeals for the relevant pre-approval assessment years cannot continue; the taxpayer's appeals succeed on this preliminary issue, the Revenue's appeals fail, and merits issues remain open.
An approved resolution plan binds governmental and statutory authorities and operates on a clean-slate basis for tax proceedings relating to pre-approval periods. Where plan clauses expressly extinguish and require withdrawal of pending tax proceedings concerning the corporate debtor, affiliates and subsidiaries, income-tax jurisdiction cannot be exercised inconsistently with the plan. A legal plea based on subsequent undisputed approval of the plan may be admitted in appellate proceedings where it goes to the root of the matter and requires no fresh factual enquiry. Income-tax appeals for the relevant pre-approval assessment years cannot continue; the taxpayer's appeals succeed on this preliminary issue, the Revenue's appeals fail, and merits issues remain open.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4899