Loading...

⚠ ✕
❮ Top
☎ Help
☰
×

By creating an account you can:

Logo TaxTMI
Call Us / Help / Feedback✕

Contact Us At :

✉ E-mail: [email protected]

✆ Call / WhatsApp at: +91 99117 96707

For more information, Check Contact Us

FAQs :

To know Frequently Asked Questions, Check FAQs

Most Asked Video Tutorials :

For more tutorials, Check Video Tutorials

Submit Feedback/Suggestion :

Email :
Please provide your email address so we can follow up on your feedback.
Category :
Description :
Min 15 characters 0/2000
Make Most of Text Search ✕
  1. Checkout this video tutorial: How to search effectively on TaxTMI.
  2. Put words in double quotes for exact word search, eg: "income tax"
  3. Avoid noise words such as : 'and, of, the, a'
  4. Sort by Relevance to get the most relevant document.
  5. Press Enter to add multiple terms/multiple phrases, and then click on Search to Search.
  6. Text Search
  7. The system will try to fetch results that contains ALL your words.
  8. Once you add keywords, you'll see a new 'Search In' filter that makes your results even more precise.
  9. Text Search
╳
Add to...
You have not created any category. Kindly create one to bookmark this item!
✕
Create New Category
Hide
Title :
Description :
❮❮ Hide
❮ Default View
Expand ❯❯
Close ✕
🔎 Filters / Advanced Search ❯
TEXT

Press 'Enter' to add multiple search terms. Rules for Better Search

Search In
Main Text + AI Text ❯
  • Main Text
  • Main Text + AI Text
  • AI Text
Law:
---- All Laws---- ❯
  • ---- All Laws----
  • Income Tax
  • Direct Taxes
  • Benami Property
  • Central GST Laws
  • SGST - State GST Laws
  • Customs
  • FTP - Foreign Trade Policy
  • SEZ - Special Economic Zone
  • FEMA - Foreign Exchange Management
  • Companies Law
  • SEBI - Securities & Exchange Board of India
  • IBC - Insolvency and Bankruptcy
  • Law of Competition
  • PMLA - Money-Laundering
  • Indian Laws
  • Bill / Finance Bills
  • Wealth Tax
  • Service Tax
  • Central Excise
  • VAT / Sales Tax
Month:
---- All Months ---- ❯
  • ---- All Months ----
  • January
  • February
  • March
  • April
  • May
  • June
  • July
  • August
  • September
  • October
  • November
  • December
Year:
---- All Years ---- ❯
  • ---- All Years ----
  • 2026
  • 2025
  • 2024
  • 2023
  • 2022
  • 2021
  • 2020
  • 2019
  • 2018
  • 2017
  • 2016
  • 2015
  • 2014
  • 2013
  • 2012
  • 2011
Sort By: ?
In Sort By 'Default', exact matches for text search are shown at the top, followed by the remaining results in their regular order.
Relevance Default Date
☰   Show Results ❯
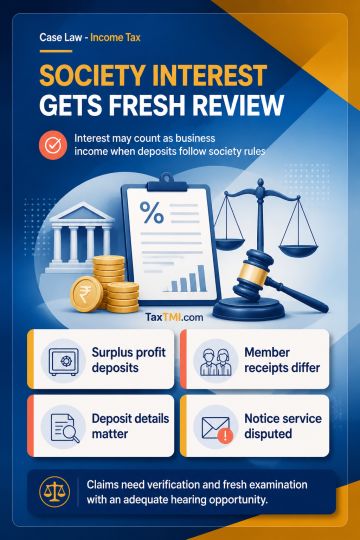
    Co-operative society deposit interest may retain business-income character, subject to statutory deposit conditions and factual verification.
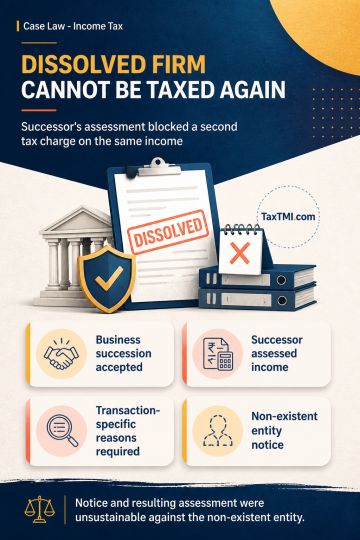
    Reassessment of a dissolved firm fails where successor income was already assessed and recorded reasons lacked transaction-specific material.
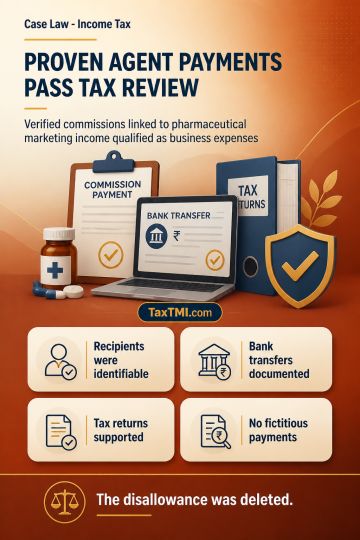
    Commission expenditure linked to pharmaceutical marketing income qualifies as business deduction when recipient identity, genuineness and business pur...
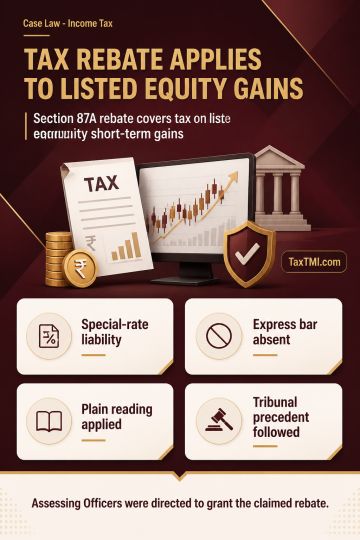
    Section 87A rebate applies to tax on listed equity short-term capital gains taxed at the special rate.
    Unabsorbed depreciation retains its character and can offset house-property income despite absence of positive business income.
    Business expenditure and hedging premium claims remain allowable, while plant-related receipts reduce capital work-in-progress.
    Captive wind-power profits use consumer tariff for deduction; unsupported payment disallowance for alleged withholding failures cannot stand.
    Indexed cost of improvement requires proof of actual works and payments; estimates and quotations cannot support the claim.
    Penny-stock sale additions require taxpayer-linked evidence, while undisclosed exempt capital gains can justify reassessment proceedings.
    Evidentiary currency seizure under customs law remains retainable despite expiry of the notice period for confiscation proceedings.
    Unjust enrichment in customs refunds fails where sales evidence proves duty incidence was not passed to buyers.
    Customs detention starts the notice limitation period, invalidating extensions issued after the original period expires.
    Customs detention without seizure requirements is arbitrary; imported goods require conditional release while assessment and adjudication continue.
    Customs show cause adjudication must meet statutory timelines; procedural amendments cannot revive stale or delayed claims.
    Country of Origin Certificates and declared transaction value supported preferential customs exemption where authenticity and invoice prices remained ...
    Social Welfare Surcharge requires actual collection of basic customs duty, not MEIS or SEIS scrip debits.
    Lawful domestic procurement evidence defeats gold confiscation when authorities fail to verify documents or prove smuggling and currency-sale links.
    Burden of proof for foreign-origin gold requires lawful import evidence; unsupported claims can trigger confiscation and penalties.
    Vegetable extract classification: standardising oil and antioxidant additions do not convert Keranat into a residual food preparation.
    Front-running allegations require SEBI's statutory complaint, barring investor FIRs that seek to prosecute securities-market offences directly.
❮
❯
❯❯
Maximize Maximize Maximize
0 / 200
Expand Note
Add to Folder

No Folders have been created

+

Are you sure you want to delete "My most important" ?

NOTE:

Highlights
Showing Results for :
Reset Filters
Results Found:
Show All Summaries Hide All Summaries

Highlights

Back

All Highlights

Showing Results for :
Reset Filters
No Records Found

Highlights

Back

All Highlights

An approved resolution plan binds governmental and statutory...

Approved resolution plans bind tax authorities and extinguish pre-approval tax appeals where plan terms require withdrawal of proceedings.

Contents
Summary
Note

Note

-

Bookmark

Print

Print

Income Tax August 19, 2026 Case Laws AT
An approved resolution plan binds governmental and statutory authorities and operates on a clean-slate basis for tax proceedings relating to pre-approval periods. Where plan clauses expressly extinguish and require withdrawal of pending tax proceedings concerning the corporate debtor, affiliates and subsidiaries, income-tax jurisdiction cannot be exercised inconsistently with the plan. A legal plea based on subsequent undisputed approval of the plan may be admitted in appellate proceedings where it goes to the root of the matter and requires no fresh factual enquiry. Income-tax appeals for the relevant pre-approval assessment years cannot continue; the taxpayer's appeals succeed on this preliminary issue, the Revenue's appeals fail, and merits issues remain open.

Topics

Acts Income Tax