Blocked input tax credit for resort construction remains unavailable; interest follows actual utilisation, while delayed payment attracts statutory pe...
Duplicate PAN allocation requires record verification and deactivation reasons before assessment-related transactions can be attributed to an assessee...
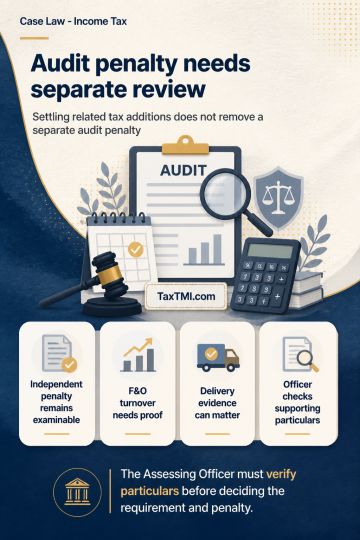
Penalty immunity under the Direct Tax Vivad Se Vishwas Scheme does not extend to an independent penalty for failure to obtain a statutory tax audit merely because related quantum additions were settled. The penalty issue remains separately examinable. For futures and options transactions, tax-audit applicability depends on evidence establishing the transaction nature and turnover computation under the ICAI Guidance Note. Where the record does not show whether transactions were futures and options or delivery-based, the tax-audit requirement and consequential penalty require factual verification by the Assessing Officer after the taxpayer provides supporting particulars.
Penalty immunity under the Direct Tax Vivad Se Vishwas Scheme does not extend to an independent penalty for failure to obtain a statutory tax audit merely because related quantum additions were settled. The penalty issue remains separately examinable. For futures and options transactions, tax-audit applicability depends on evidence establishing the transaction nature and turnover computation under the ICAI Guidance Note. Where the record does not show whether transactions were futures and options or delivery-based, the tax-audit requirement and consequential penalty require factual verification by the Assessing Officer after the taxpayer provides supporting particulars.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4884