Alternative statutory remedy under GST bars writ challenge where classification, notice variance, and hearing disputes require factual appellate revie...
Duplicate PAN cancellation timeframe requires prior administrative representation before judicial intervention, ensuring a time-bound decision on the ...
Natural justice and pre-CIRP labour awards protect termination compensation, permitting withdrawal of court deposits despite later insolvency resoluti...
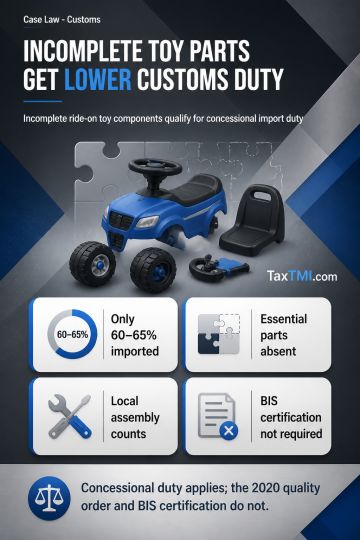
Imported electric ride-on toy components comprising only 60-65% of the parts needed for a complete toy, with essential components absent, are treated as toy parts rather than complete toys in CKD/SKD condition. Assembly with locally procured or manufactured components and subsequent testing produces a distinct finished product and constitutes manufacture under the concessional-duty import rules. Such imports are classified under CTH 95030091 and qualify for concessional customs-duty exemption under Notification No. 50/2017-Cus. The Toys (Quality Control) Order, 2020 does not apply because toy parts cannot independently be regarded as toys and BIS certification is not required for them.
Imported electric ride-on toy components comprising only 60-65% of the parts needed for a complete toy, with essential components absent, are treated as toy parts rather than complete toys in CKD/SKD condition. Assembly with locally procured or manufactured components and subsequent testing produces a distinct finished product and constitutes manufacture under the concessional-duty import rules. Such imports are classified under CTH 95030091 and qualify for concessional customs-duty exemption under Notification No. 50/2017-Cus. The Toys (Quality Control) Order, 2020 does not apply because toy parts cannot independently be regarded as toys and BIS certification is not required for them.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4897