Loading...

Top
Help
×

By creating an account you can:

Logo TaxTMI
Call Us / Help / Feedback

Contact Us At :

E-mail: [email protected]

Call / WhatsApp at: +91 99117 96707

For more information, Check Contact Us

FAQs :

To know Frequently Asked Questions, Check FAQs

Most Asked Video Tutorials :

For more tutorials, Check Video Tutorials

Submit Feedback/Suggestion :

Email :
Please provide your email address so we can follow up on your feedback.
Category :
Description :
Min 15 characters 0/2000
Make Most of Text Search
  1. Checkout this video tutorial: How to search effectively on TaxTMI.
  2. Put words in double quotes for exact word search, eg: "income tax"
  3. Avoid noise words such as : 'and, of, the, a'
  4. Sort by Relevance to get the most relevant document.
  5. Press Enter to add multiple terms/multiple phrases, and then click on Search to Search.
  6. Text Search
  7. The system will try to fetch results that contains ALL your words.
  8. Once you add keywords, you'll see a new 'Search In' filter that makes your results even more precise.
  9. Text Search
Add to...
You have not created any category. Kindly create one to bookmark this item!
Create New Category
Hide
Title :
Description :
❮❮ Hide
Default View
Expand ❯❯
Close ✕
🔎 Highlights - Adv. Search
TEXT SEARCH:

Press 'Enter' to add multiple search terms. Rules for Better Search

Search In:
Main Text + AI Text
  • Main Text
  • Main Text + AI Text
  • AI Text
Law:
---- All Laws----
  • ---- All Laws----
  • Income Tax
  • Direct Taxes
  • Benami Property
  • Central GST Laws
  • SGST - State GST Laws
  • Customs
  • FTP - Foreign Trade Policy
  • SEZ - Special Economic Zone
  • FEMA - Foreign Exchange Management
  • Companies Law
  • SEBI - Securities & Exchange Board of India
  • IBC - Insolvency and Bankruptcy
  • Law of Competition
  • PMLA - Money-Laundering
  • Indian Laws
  • Bill / Finance Bills
  • Wealth Tax
  • Service Tax
  • Central Excise
  • VAT / Sales Tax
Month:
---- All Months ----
  • ---- All Months ----
  • January
  • February
  • March
  • April
  • May
  • June
  • July
  • August
  • September
  • October
  • November
  • December
Year:
---- All Years ----
  • ---- All Years ----
  • 2026
  • 2025
  • 2024
  • 2023
  • 2022
  • 2021
  • 2020
  • 2019
  • 2018
  • 2017
  • 2016
  • 2015
  • 2014
  • 2013
  • 2012
  • 2011
Sort By: ?
In Sort By 'Default', exact matches for text search are shown at the top, followed by the remaining results in their regular order.
Relevance Default Date
    Road and Infrastructure Cess on exported petrol and diesel is reduced to nil from the notification's effective date.
    Special additional excise duty on exported aviation turbine fuel is revised, applying from Official Gazette publication.
    Special additional excise duty on petrol and diesel exports revised, with new rates effective upon Gazette publication.
    Evidentiary safeguards for statements and electronic records defeated a clandestine-clearance demand lacking independent corroboration entirely.
    Brand-name use on goods, not invoices, preserves vanaspati exemption and defeats duty demand and penalty.
    Rule 41 implementation directions remain outside appellate review, while mistaken service-tax payments attract compensatory interest from the original...
    Portable rechargeable lamp classification under Heading 8513 prevails, while disclosed tariff disputes bar extended limitation and penalties.
    Penalty for dealing in confiscable goods requires proof of knowing involvement and a complete evidentiary chain.
    Road and Infrastructure Cess on exported petrol and diesel is revised to a uniform per-litre rate.
    Special Additional Excise Duty on exported Aviation Turbine Fuel is revised through a substituted effective duty rate.
    Central excise rate amendment substitutes the serial-number-one table entry with a per-litre rate from Gazette publication.
    Excise assessment at removal protects PDS kerosene from duty claims on post-clearance pipeline interface formation.
    CENVAT credit on contractor-procured capital goods remains available when factory receipt supports captive manufacturing installation.
    Annual production capacity determinations excluding stenter galleries support refunds for unconstitutional excise levies without an unjust-enrichment ...
    Recovery of suo motu excise credit as erroneous refund is time-barred after the applicable limitation period expires.
    Interest on refundable revenue deposits runs from deposit date, while blanket enhanced interest awards require case-specific justification.
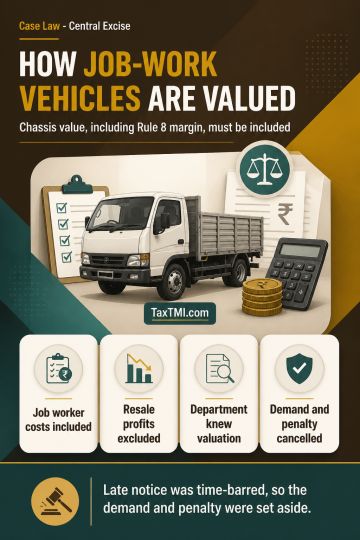
    Job-work vehicle valuation includes the Rule 8 chassis margin, but departmental knowledge defeats extended limitation for alleged suppression.
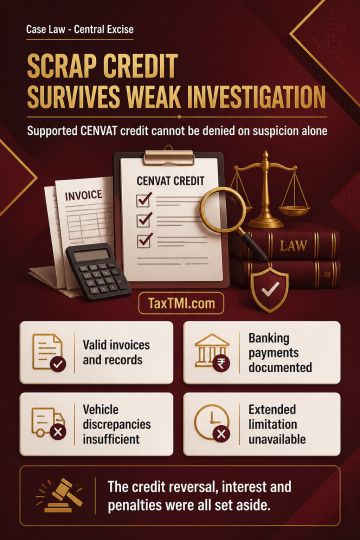
    CENVAT credit supported by invoices and records cannot be denied on uncorroborated statements or limited vehicle-data discrepancies.
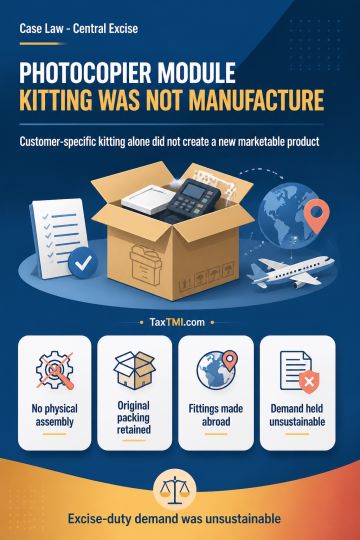
    Manufacture requires a distinct marketable commodity; photocopier module kitting without assembly does not attract central excise duty.
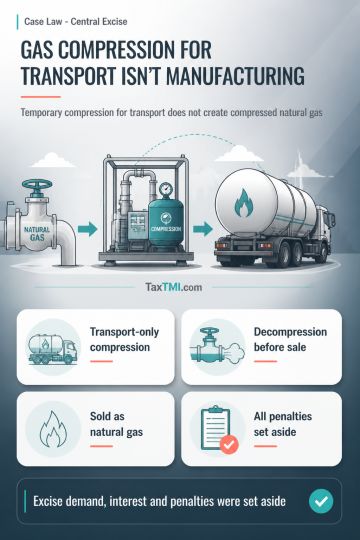
    Natural gas compression solely for transport, followed by decompression before sale, does not constitute manufacture of compressed natural gas.
❯❯
Maximize Maximize Maximize
0 / 200
Expand Note
Add to Folder

No Folders have been created

+

Are you sure you want to delete "My most important" ?

NOTE:

Highlights
Showing Results for :
Reset Filters
Results Found:
Show All Summaries Hide All Summaries

Highlights

Back

All Highlights

Showing Results for :
Reset Filters
No Records Found

Highlights

Back

All Highlights

Showing Results for : Reset Filters
Central Excise

Interest on refundable revenue deposits, including unspent...

Interest on refundable revenue deposits runs from deposit date, while blanket enhanced interest awards require case-specific justification.

Contents
Summary
Note

Note

-

Bookmark

Print

Print

Central Excise August 19, 2026 Case Laws AT
Interest on refundable revenue deposits, including unspent Personal Ledger Account balances, is payable from the date of deposit where amounts were deposited during investigation before any duty liability was determined and therefore retained the character of revenue deposits. The majority view rejected the Revenue's challenge to interest from the deposit date and dismissed both appeals. The discussion distinguishes statutory and equitable interest and rejects blanket awards of 12% interest based solely on Sandvik, requiring consideration of relevant factors and later Supreme Court guidance. The majority treated the jurisdictional High Court ruling in Parle Agro as governing the entitlement to interest from the deposit date.

Topics

Acts Income Tax