Co-operative deduction eligibility excludes refund and commercial-bank interest, while qualifying co-operative investments require entity-wise verific...
Enhanced tax rate on surrendered unexplained income applies prospectively, while cash-deposit telescoping requires verification of available surrender...
Customs Broker licence proceedings require accurate procedural facts before delay or natural-justice findings can justify setting aside regulatory act...
Provisional assessment finalisation must precede export duty recovery, while redemption fine fails for goods already exported and unavailable for conf...
Page of 4896
Press 'Enter' after typing page number.
1921 to 1940 of 97907 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
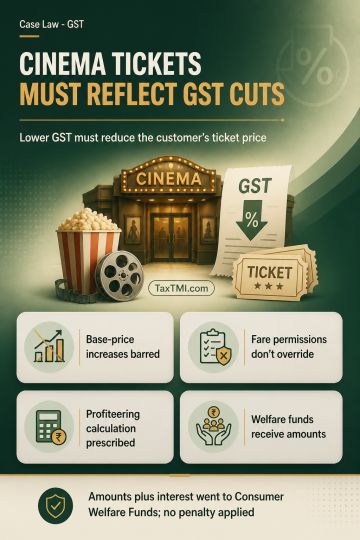
Section 171(1) requires GST rate reductions to produce a commensurate reduction in the price payable by cinema-ticket recipients; charging GST at the reduced rate alone is insufficient where the operator increases the pre-tax base price and retains the same cum-tax fare. Regulatory permissions concerning maximum or proposed ticket fares do not displace this independent anti-profiteering obligation, particularly without competent approval of enhanced rates. Profiteering may be quantified by retaining the pre-rate-reduction base price, applying the reduced GST rate to determine the commensurate price, and comparing it with actual ticket sales. Where recipients cannot be identified, the determined amount with applicable interest is deposited in the Consumer Welfare Funds; no penalty applied for the investigation period.
Section 171(1) requires GST rate reductions to produce a commensurate reduction in the price payable by cinema-ticket recipients; charging GST at the reduced rate alone is insufficient where the operator increases the pre-tax base price and retains the same cum-tax fare. Regulatory permissions concerning maximum or proposed ticket fares do not displace this independent anti-profiteering obligation, particularly without competent approval of enhanced rates. Profiteering may be quantified by retaining the pre-rate-reduction base price, applying the reduced GST rate to determine the commensurate price, and comparing it with actual ticket sales. Where recipients cannot be identified, the determined amount with applicable interest is deposited in the Consumer Welfare Funds; no penalty applied for the investigation period.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4896