Charitable registration renewal cannot become an assessment of receipts, profitability or annual exemption compliance, requiring renewal and donation ...
AMP expenditure for own business is not an international transaction without an associated-enterprise arrangement, eliminating transfer pricing adjust...
Customs valuation must use comparable contemporary imports, while confiscation fines and penalties require proportionate recalculation on reassessed v...
Depositor-protection proceedings prevail over corporate insolvency, while liquidators may recover chit receivables using copies of seized company reco...
Intermediary service classification fails where overseas admission facilitation is supplied independently, preserving export treatment and small-provi...
Satellite transponder bandwidth is telecommunication, not Business Support Service; foreign non-telegraph providers triggered no service tax liability...
Page of 4897
Press 'Enter' after typing page number.
1901 to 1920 of 97923 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
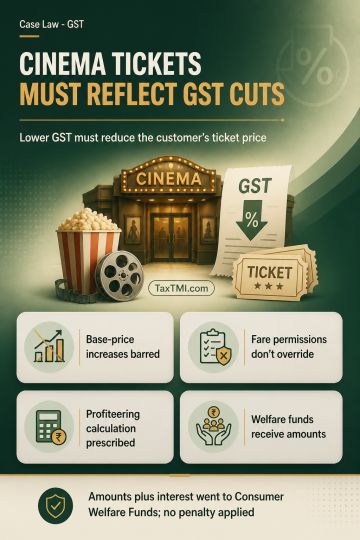
Section 171(1) requires GST rate reductions to produce a commensurate reduction in the price payable by cinema-ticket recipients; charging GST at the reduced rate alone is insufficient where the operator increases the pre-tax base price and retains the same cum-tax fare. Regulatory permissions concerning maximum or proposed ticket fares do not displace this independent anti-profiteering obligation, particularly without competent approval of enhanced rates. Profiteering may be quantified by retaining the pre-rate-reduction base price, applying the reduced GST rate to determine the commensurate price, and comparing it with actual ticket sales. Where recipients cannot be identified, the determined amount with applicable interest is deposited in the Consumer Welfare Funds; no penalty applied for the investigation period.
Section 171(1) requires GST rate reductions to produce a commensurate reduction in the price payable by cinema-ticket recipients; charging GST at the reduced rate alone is insufficient where the operator increases the pre-tax base price and retains the same cum-tax fare. Regulatory permissions concerning maximum or proposed ticket fares do not displace this independent anti-profiteering obligation, particularly without competent approval of enhanced rates. Profiteering may be quantified by retaining the pre-rate-reduction base price, applying the reduced GST rate to determine the commensurate price, and comparing it with actual ticket sales. Where recipients cannot be identified, the determined amount with applicable interest is deposited in the Consumer Welfare Funds; no penalty applied for the investigation period.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4897