Personal liberty safeguards restrict arrest after court-directed GST appearance, requiring interim release where authorities overreach pending proceed...
Alternative statutory remedy and delay bar GST writ challenges despite pending rectification, while distinct subject matter permits parallel proceedin...
Unverified Insight Portal Information Cannot Justify Reassessment Without a Verified Taxpayer-Specific Income-Escape Nexus or Demonstrated Application...
Assessing Officer jurisdiction after statutory transfer invalidates reassessment notices issued by transferor officers and nullifies resulting proceed...
Consequential appeal-effect orders must implement rectification deleting working-capital adjustments and reconsider the resulting arm's-length range c...
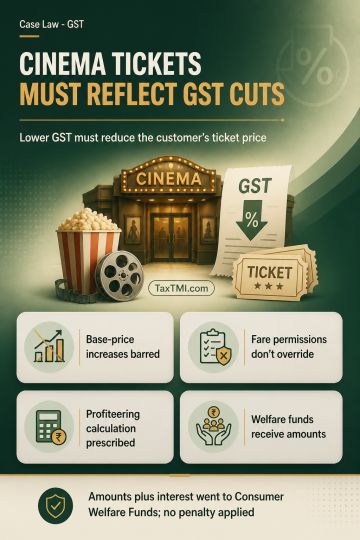
Section 171(1) requires GST rate reductions to produce a commensurate reduction in the price payable by cinema-ticket recipients; charging GST at the reduced rate alone is insufficient where the operator increases the pre-tax base price and retains the same cum-tax fare. Regulatory permissions concerning maximum or proposed ticket fares do not displace this independent anti-profiteering obligation, particularly without competent approval of enhanced rates. Profiteering may be quantified by retaining the pre-rate-reduction base price, applying the reduced GST rate to determine the commensurate price, and comparing it with actual ticket sales. Where recipients cannot be identified, the determined amount with applicable interest is deposited in the Consumer Welfare Funds; no penalty applied for the investigation period.
Section 171(1) requires GST rate reductions to produce a commensurate reduction in the price payable by cinema-ticket recipients; charging GST at the reduced rate alone is insufficient where the operator increases the pre-tax base price and retains the same cum-tax fare. Regulatory permissions concerning maximum or proposed ticket fares do not displace this independent anti-profiteering obligation, particularly without competent approval of enhanced rates. Profiteering may be quantified by retaining the pre-rate-reduction base price, applying the reduced GST rate to determine the commensurate price, and comparing it with actual ticket sales. Where recipients cannot be identified, the determined amount with applicable interest is deposited in the Consumer Welfare Funds; no penalty applied for the investigation period.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4894