Infrastructure-development deduction remains available to EPC contractors when substantive statutory conditions outweigh contractor labels in agreemen...
Explained Investment Sources: documented gifts and traceable salary savings supported deletion of additions for property and mutual-fund SIP investmen...
Internal comparable pricing supports arm's-length interest on compulsorily convertible debentures, preventing their recharacterisation as equity for t...
Nominee director protection shields independent financial-institution appointees from criminal liability where they lack involvement in deposit defaul...
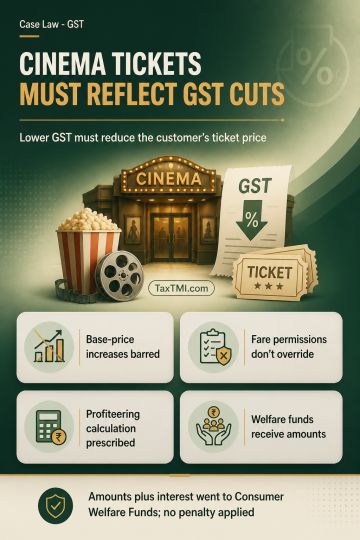
Section 171(1) requires GST rate reductions to produce a commensurate reduction in the price payable by cinema-ticket recipients; charging GST at the reduced rate alone is insufficient where the operator increases the pre-tax base price and retains the same cum-tax fare. Regulatory permissions concerning maximum or proposed ticket fares do not displace this independent anti-profiteering obligation, particularly without competent approval of enhanced rates. Profiteering may be quantified by retaining the pre-rate-reduction base price, applying the reduced GST rate to determine the commensurate price, and comparing it with actual ticket sales. Where recipients cannot be identified, the determined amount with applicable interest is deposited in the Consumer Welfare Funds; no penalty applied for the investigation period.
Section 171(1) requires GST rate reductions to produce a commensurate reduction in the price payable by cinema-ticket recipients; charging GST at the reduced rate alone is insufficient where the operator increases the pre-tax base price and retains the same cum-tax fare. Regulatory permissions concerning maximum or proposed ticket fares do not displace this independent anti-profiteering obligation, particularly without competent approval of enhanced rates. Profiteering may be quantified by retaining the pre-rate-reduction base price, applying the reduced GST rate to determine the commensurate price, and comparing it with actual ticket sales. Where recipients cannot be identified, the determined amount with applicable interest is deposited in the Consumer Welfare Funds; no penalty applied for the investigation period.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881