Transfer-pricing comparability permits fresh objections and filters where software service comparables are functionally unsuitable for arm's-length pr...
Territorial rendering requirement excludes China-based management and consultancy services from fees for technical services under the India-China DTAA...
FEMA borrowing restrictions bind charitable trusts, and civil penalties apply without proving intent for delayed repayment of non-resident rupee loans...
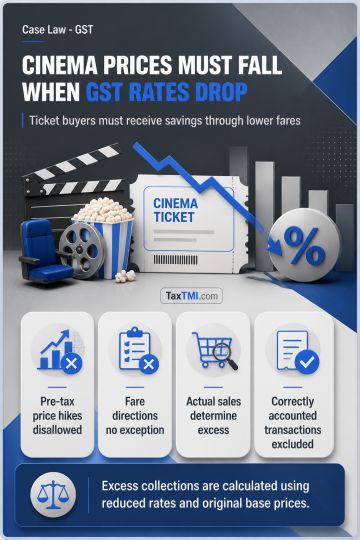
Section 171(1) requires GST rate-reduction benefits on cinema admission tickets to be passed to recipients through a commensurate reduction in cum-tax ticket prices. Retaining the same ticket price by increasing the pre-tax base price does not satisfy this obligation. Directions permitting collection of proposed cinema fares and representations to licensing authorities do not create an exception to the anti-profiteering requirement, particularly where approval is unsubstantiated or relates to later periods. Profiteering may be quantified by retaining the pre-reduction base price, applying the reduced GST rate to determine the commensurate price, and calculating excess collections from actual ticket sales, while excluding correctly accounted transactions at other rates.
Section 171(1) requires GST rate-reduction benefits on cinema admission tickets to be passed to recipients through a commensurate reduction in cum-tax ticket prices. Retaining the same ticket price by increasing the pre-tax base price does not satisfy this obligation. Directions permitting collection of proposed cinema fares and representations to licensing authorities do not create an exception to the anti-profiteering requirement, particularly where approval is unsubstantiated or relates to later periods. Profiteering may be quantified by retaining the pre-reduction base price, applying the reduced GST rate to determine the commensurate price, and calculating excess collections from actual ticket sales, while excluding correctly accounted transactions at other rates.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881