Food import sampling requirements support provisional release where unseized consignments conform to standards and raw areca classification is unestab...
Diagnostic microcuvette classification follows sole-use analytical function, placing specialised disposable cuvettes with their analyser rather than g...
Customs Broker licensing proceedings fail when their offence-report foundation collapses and authorisation, advisory, and KYC duties remain unbreached...
Tariff classification of Digital Axle Counters affirmed as electro-mechanical railway signalling equipment, eliminating duty, confiscation and penalty...
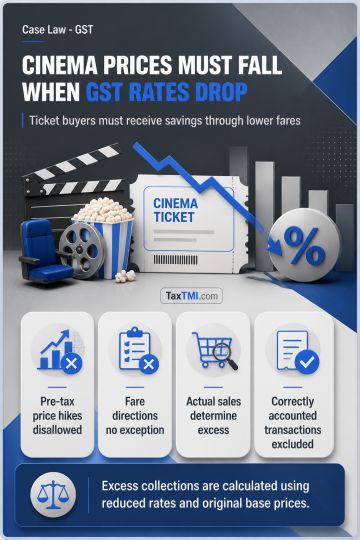
Section 171(1) requires GST rate-reduction benefits on cinema admission tickets to be passed to recipients through a commensurate reduction in cum-tax ticket prices. Retaining the same ticket price by increasing the pre-tax base price does not satisfy this obligation. Directions permitting collection of proposed cinema fares and representations to licensing authorities do not create an exception to the anti-profiteering requirement, particularly where approval is unsubstantiated or relates to later periods. Profiteering may be quantified by retaining the pre-reduction base price, applying the reduced GST rate to determine the commensurate price, and calculating excess collections from actual ticket sales, while excluding correctly accounted transactions at other rates.
Section 171(1) requires GST rate-reduction benefits on cinema admission tickets to be passed to recipients through a commensurate reduction in cum-tax ticket prices. Retaining the same ticket price by increasing the pre-tax base price does not satisfy this obligation. Directions permitting collection of proposed cinema fares and representations to licensing authorities do not create an exception to the anti-profiteering requirement, particularly where approval is unsubstantiated or relates to later periods. Profiteering may be quantified by retaining the pre-reduction base price, applying the reduced GST rate to determine the commensurate price, and calculating excess collections from actual ticket sales, while excluding correctly accounted transactions at other rates.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4888