Capital-gains exemption for charitable trusts extends to qualifying fixed deposits, while unrecoverable TDS write-offs may constitute income applicati...
India-UK treaty characterisation of telecom-service receipts as business profits withstands unilateral domestic-law amendments for Indian tax purposes...
Transfer-pricing reimbursement adjustments require uncontrolled comparables and cannot become expense-genuineness reviews, resulting in deletion of th...
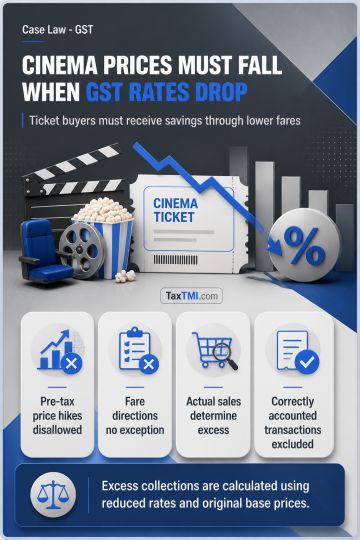
Section 171(1) requires GST rate-reduction benefits on cinema admission tickets to be passed to recipients through a commensurate reduction in cum-tax ticket prices. Retaining the same ticket price by increasing the pre-tax base price does not satisfy this obligation. Directions permitting collection of proposed cinema fares and representations to licensing authorities do not create an exception to the anti-profiteering requirement, particularly where approval is unsubstantiated or relates to later periods. Profiteering may be quantified by retaining the pre-reduction base price, applying the reduced GST rate to determine the commensurate price, and calculating excess collections from actual ticket sales, while excluding correctly accounted transactions at other rates.
Section 171(1) requires GST rate-reduction benefits on cinema admission tickets to be passed to recipients through a commensurate reduction in cum-tax ticket prices. Retaining the same ticket price by increasing the pre-tax base price does not satisfy this obligation. Directions permitting collection of proposed cinema fares and representations to licensing authorities do not create an exception to the anti-profiteering requirement, particularly where approval is unsubstantiated or relates to later periods. Profiteering may be quantified by retaining the pre-reduction base price, applying the reduced GST rate to determine the commensurate price, and calculating excess collections from actual ticket sales, while excluding correctly accounted transactions at other rates.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4888