Ratification of resignation acceptance validates separation retrospectively, while withdrawal may be refused through reasoned administrative discretio...
Nature-dependent electricity contracts receive new Ind AS accounting, hedge designation, transition and financial-statement disclosure requirements fr...
Alternative GST remedy permitted protective writ intervention for ex parte adjudication, preserving independent appellate review of input tax credit d...
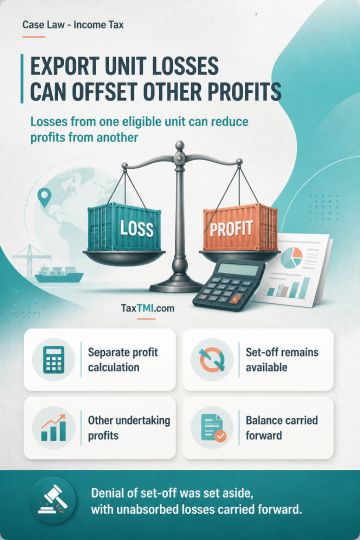
Section 10B requires separate computation of export profits for each eligible software-export undertaking only to quantify the deduction. That separate computation does not alter the undertaking's profit or loss for computing combined income, nor does it displace the normal rules for inter-source and inter-head set-off and carry forward of losses. Losses of a Section 10B-eligible undertaking may therefore be set off against profits of other undertakings, with any unabsorbed balance carried forward in accordance with law. The contrary denial of set-off was set aside.
Section 10B requires separate computation of export profits for each eligible software-export undertaking only to quantify the deduction. That separate computation does not alter the undertaking's profit or loss for computing combined income, nor does it displace the normal rules for inter-source and inter-head set-off and carry forward of losses. Losses of a Section 10B-eligible undertaking may therefore be set off against profits of other undertakings, with any unabsorbed balance carried forward in accordance with law. The contrary denial of set-off was set aside.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4897