GST payment representations require record-based, reasoned decisions while substantive entitlement remains open for determination by competent authori...
Reassessment sanction under extended limitation required approval from the competent specified authority, invalidating proceedings approved by an inco...
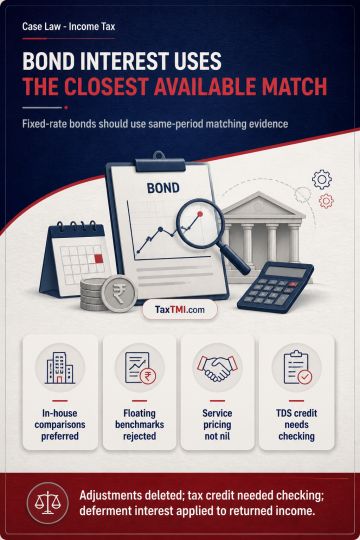
Internal CUP benchmarking for fixed-rate Masala Bonds prevails over floating external comparables, eliminating the related transfer-pricing adjustment...
Jurisdictional validity of revision notices: incorrect official capacity and mere change of opinion invalidate revision of property income assessments...
Third-party search assessments under section 153C require the seized material to be handed over to the other person's Assessing Officer before the statutory cut-off. Where handover occurs after 1 April 2021, section 153C is unavailable and proceedings may be pursued only under reassessment provisions; the resulting notice and assessment lack jurisdiction. Penalty for cash acceptance contrary to section 269SS, when unrelated to assessment, is subject to the limitation period beginning with the Assessing Officer's recommendation to initiate penalty proceedings. A penalty order issued after that period is time-barred and liable to be quashed.
Third-party search assessments under section 153C require the seized material to be handed over to the other person's Assessing Officer before the statutory cut-off. Where handover occurs after 1 April 2021, section 153C is unavailable and proceedings may be pursued only under reassessment provisions; the resulting notice and assessment lack jurisdiction. Penalty for cash acceptance contrary to section 269SS, when unrelated to assessment, is subject to the limitation period beginning with the Assessing Officer's recommendation to initiate penalty proceedings. A penalty order issued after that period is time-barred and liable to be quashed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4925